
Arnott Announces Appointment of Aalok Joshi as Chief Revenue Officer to Support Continued Growth and Customer Success
Source: PR Newswire
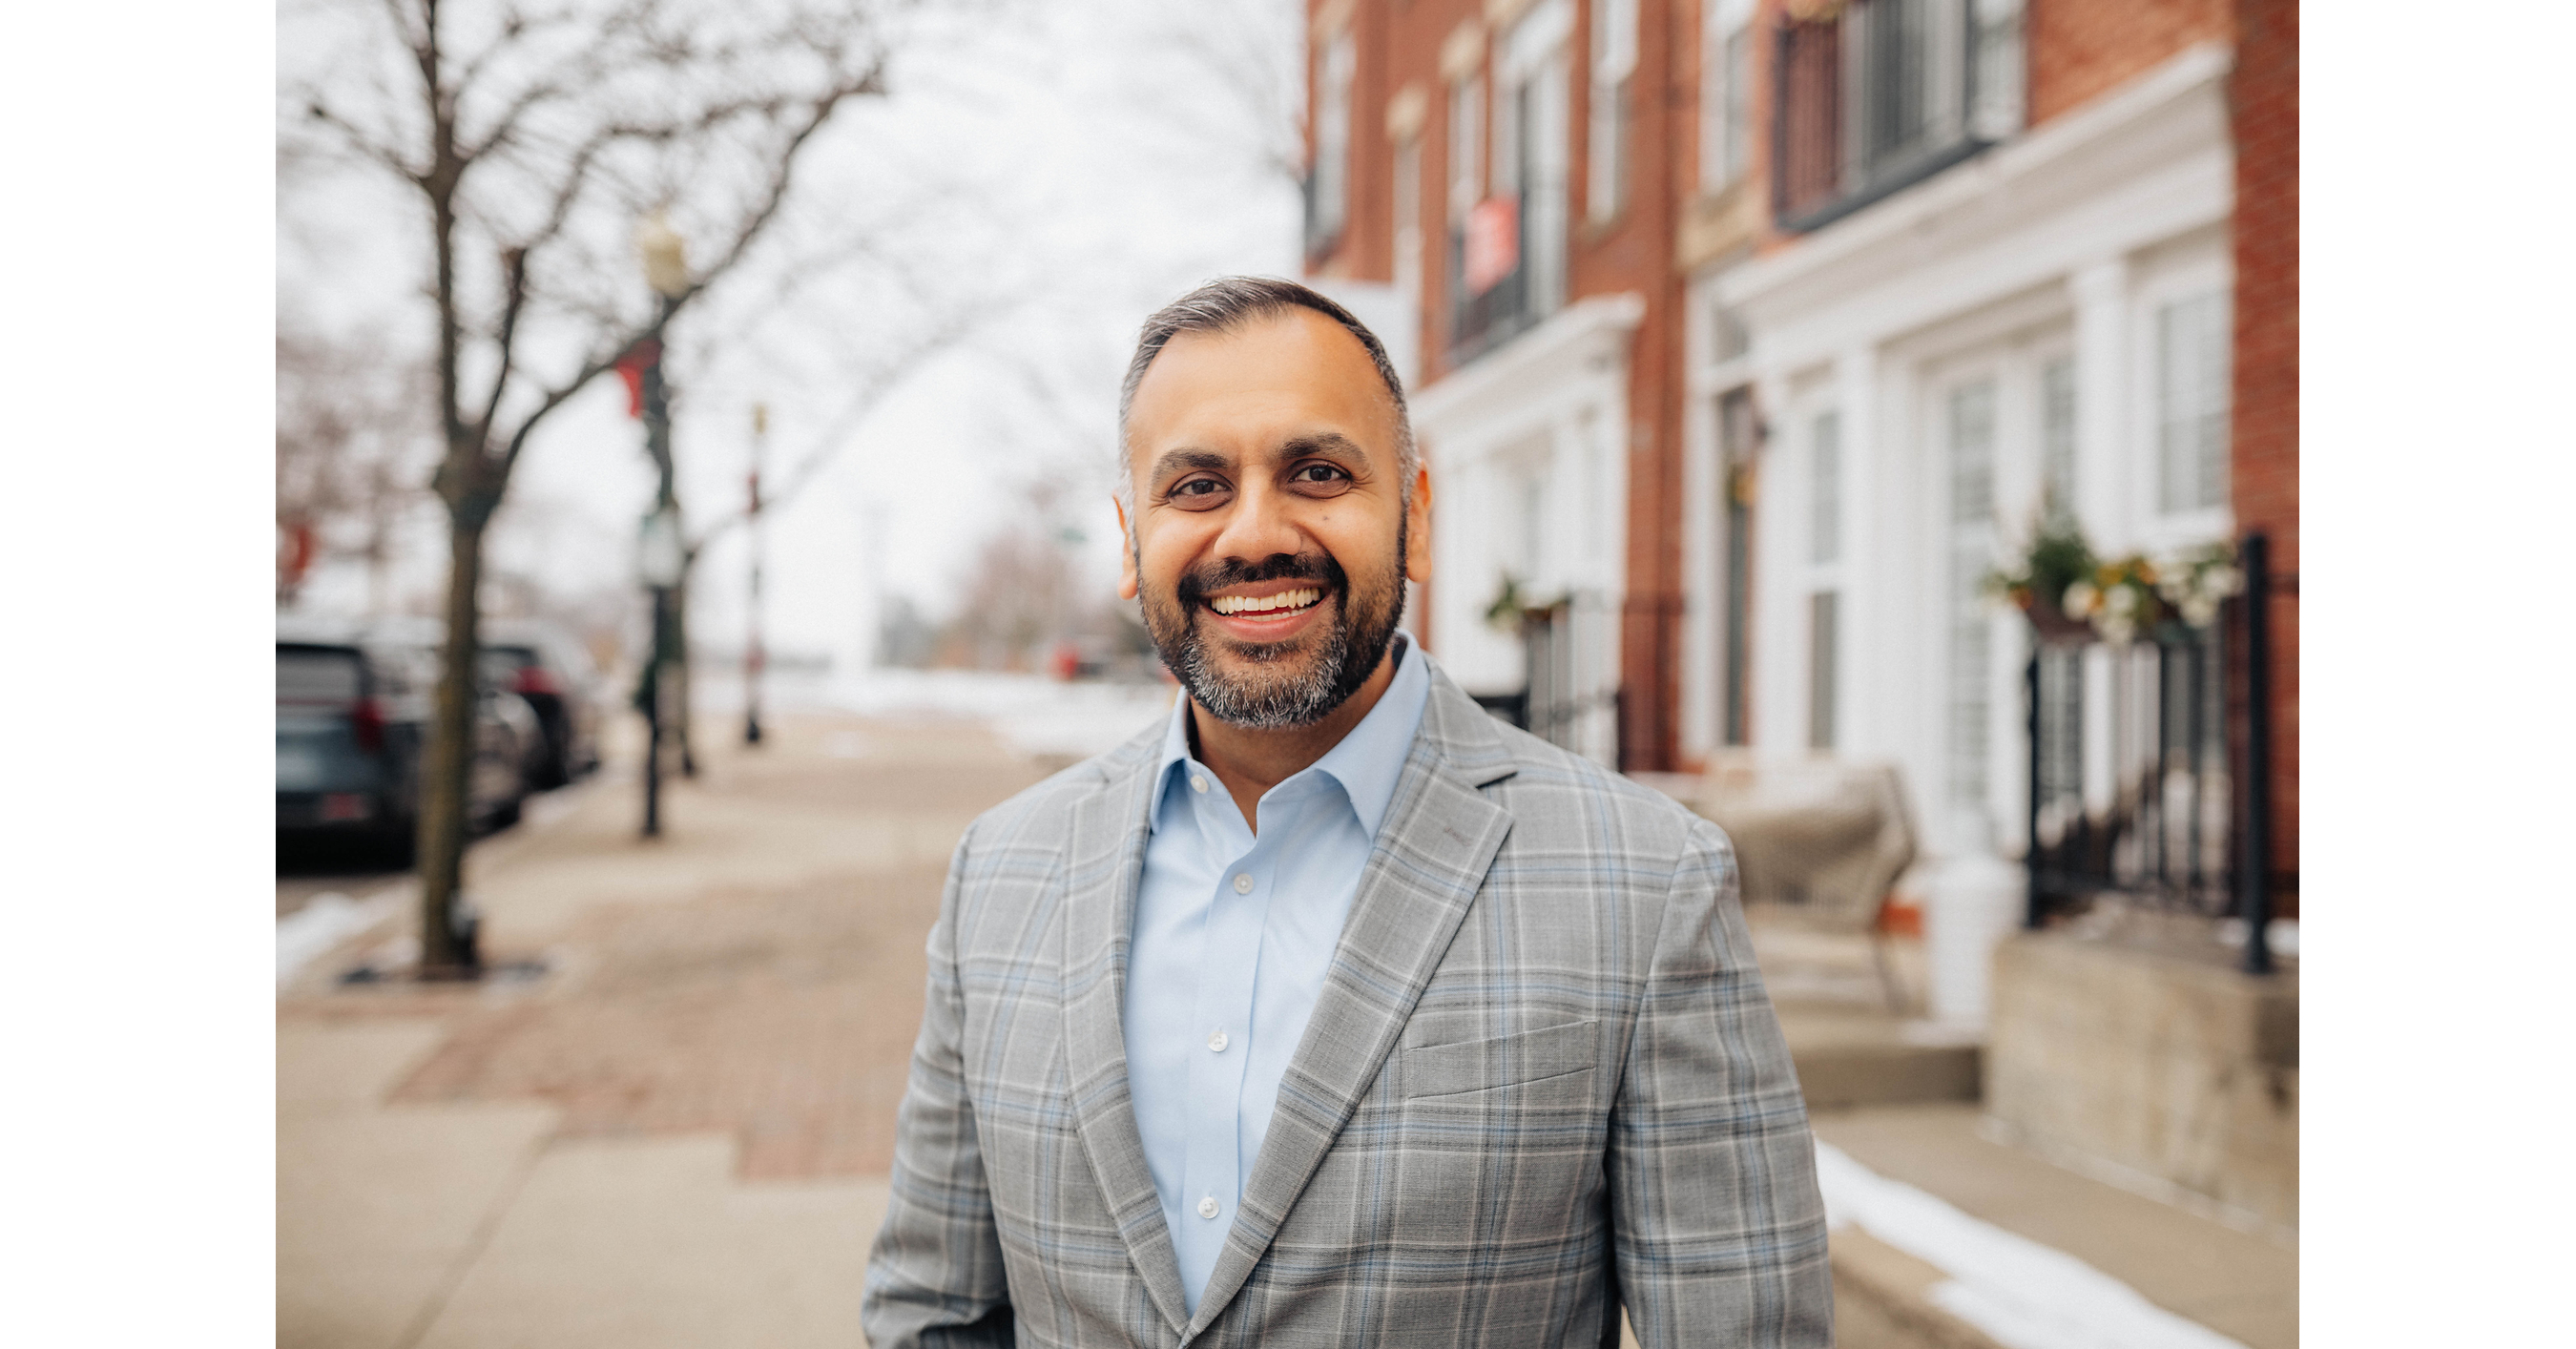
Arnott appointed Aalok Joshi as Chief Revenue Officer in a newly created role, tasking him with strengthening customer partnerships and supporting continued global growth. The company emphasized aligning sales, marketing, customer experience, and growth initiatives as part of broader investment in its capabilities. Overall, the announcement is a modestly positive management-development signal with limited near-term market impact.
Analysis
This reads more like an operating-system upgrade than a demand event. A newly created CRO role at a private aftermarket supplier usually matters only if the company is trying to professionalize a fragmented route-to-market, improve distributor conversion, or prepare for a channel expansion push; none of that changes near-term vehicle miles driven or replacement demand. The second-order signal is that management thinks commercial execution, not product, is the bottleneck — which can be constructive for share gains, but typically takes 2-4 quarters to show up in sell-through and 6-18 months to change the margin profile.
For competitors, the risk is not category growth leakage but customer wallet-share drift toward the better-run premium brand if Arnott uses the new role to tighten availability, pricing discipline, and account coverage. That would pressure smaller suspension aftermarket players and low-end import brands first, then force larger distributors to allocate more shelf/online visibility to the best service levels. The public-market spillover is likely most visible in aftermarket distribution names (ORLY, AZO, GPC) only if this translates into higher fill rates or a broader SKU footprint; otherwise the impact is de minimis.
Contrarian view: the market often over-interprets executive appointments as a growth inflection, but in this segment a CRO can just as easily be a response to uneven execution, customer concentration, or channel conflict. The thesis would be falsified if over the next 1-2 quarters there is no measurable improvement in organic growth, gross margin, or inventory turns; that would suggest this is governance theater rather than a commercial catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Key Decisions for Investors
- No direct public-equity trade: Arnott is private and the appointment is too small a catalyst to justify a sector position; treat as a watch item only over the next 2 quarters.
- Monitor ORLY and AZO for any evidence of suspension-category shelf expansion or improved fill rates in upcoming calls; if visible, that would support a modest long bias over 3-6 months, but expected impact is low.
- Watch GPC as a secondary beneficiary if better premium aftermarket execution lifts distributor mix; only actionable if management commentary points to broader hard-parts strength, otherwise keep flat.
- Set a falsification alert on any future Arnott operational metrics that fail to improve by the next earnings cycle; absent organic growth acceleration, assume the CRO hire is non-catalytic.
More News
- Bending Spoons wants to revive software castoffs. Berkshire is backing the plan
- ‘How many canaries have we killed in the coal mine?’ — Wall Street debates if the latest AI bubble warnings are another head fake or the real thing
- Alphabet’s chief investment officer responds to Jefferies warning that the most likely outcome of the AI boom is massive U.S. capital destruction
- A 44-minute call and a memo: How Alexandr Wang won Mark Zuckerberg’s trust—and a $100 billion-plus AI bet
- TSMC posts a sixth straight record profit but turns cautious on 2027
- Ericsson’s organic sales rise 7% as it merges its two Asian units
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What a Concept From Nature Tells Us About How C-Suite Executives Actually Think About AI
- How to Track Earnings Call Sentiment Across Companies