
Fruit Attraction 2026 connects Middle East buyers with the global fresh produce supply chain
Source: PR Newswire
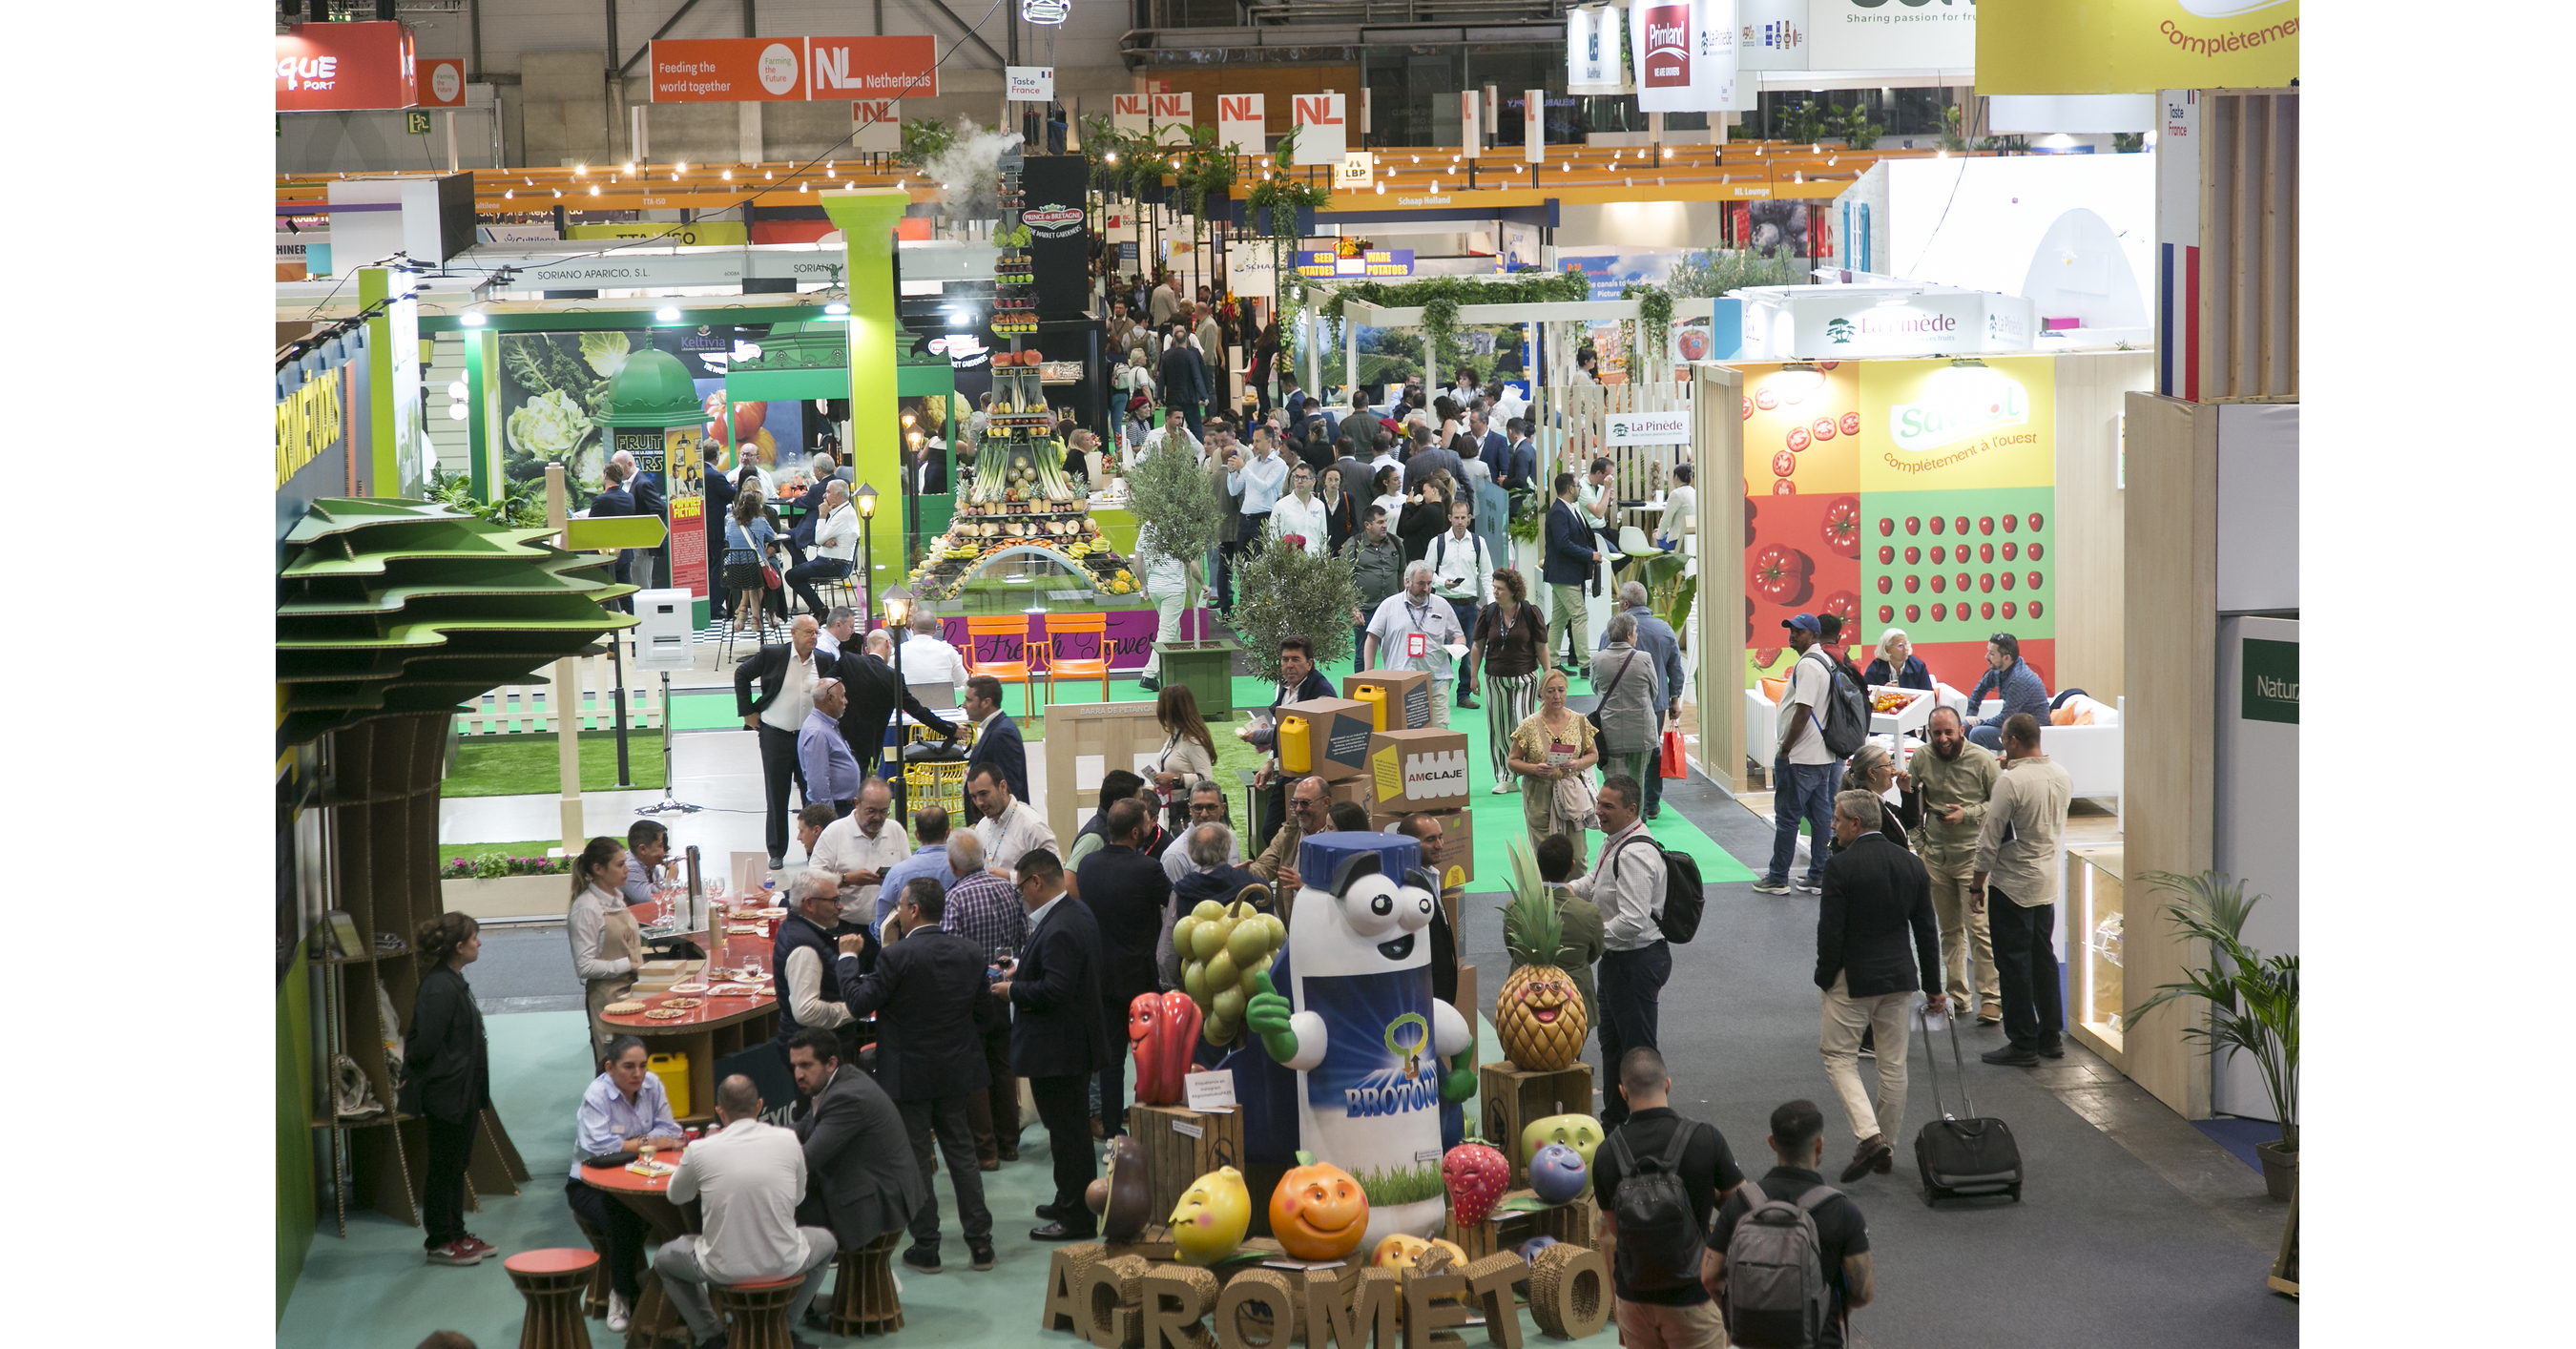
Fruit Attraction 2026, to be held in Madrid on October 6-8, expects more than 2,500 exhibitors, 121,000 trade professionals from over 150 countries, and 162,000 square metres of exhibition space. The event's International Buyers Program will bring 700 buyers and purchasing decision-makers from more than 50 countries, while China and the UAE will participate as guest importing countries. The trade show is positioned as a business-development and sourcing platform for the global fresh-produce supply chain, including expanded Middle East engagement.
Analysis
This is a low-signal promotional item rather than evidence of incremental produce volumes, contracted trade flows, or pricing power. The only potentially investable implication is that Gulf buyers are continuing to diversify perishable-food sourcing; over 6-18 months, that marginally favors cold-chain and controlled-environment agriculture infrastructure over commodity growers, whose realized pricing remains governed by weather, freight rates, and retailer bargaining power.
Public-market exposure is indirect. Lineage (LINE) and Americold (COLD) could benefit only if new sourcing corridors translate into sustained refrigerated-storage throughput, while Kuehne+Nagel (KNIN SW), DSV (DSV DC), and Maersk (MAERSK-B DC) have greater exposure to reefer logistics but limited earnings sensitivity to a trade-show pipeline. European produce retailers and growers should not be repriced on this announcement: buyer meetings are not purchase commitments, and Middle East destination growth can increase supplier competition as readily as it expands volumes.
Near term, no broad equity catalyst exists. The relevant 1-3 month confirmation would be disclosed multi-year procurement agreements, new reefer capacity bookings, or agricultural-market-access approvals involving UAE/China; absent these, the event is unlikely to alter estimates. The contrarian conclusion is that a greater supplier set may pressure origin margins and reduce the scarcity premium for established Mediterranean exporters, particularly during normal harvest years.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- No directional trade on the event itself; maintain a watchlist rather than initiate exposure, as there is no disclosed revenue, volume, or contract data to underwrite earnings revisions.
- Monitor LINE and COLD for 6-18 month evidence of incremental international refrigerated throughput or Gulf-linked capacity commitments; consider a long only after management quantifies utilization or EBITDA contribution. Falsifier: flat same-store warehouse revenue/utilization despite announced corridor expansion.
- For liquid European logistics exposure, monitor KNIN SW and DSV DC against reefer-rate indices and Middle East import-volume data; a long is warranted only if reefer yields improve while general freight capacity remains disciplined. Falsifier: falling reefer spot rates or renewed broad container-rate compression.
- Treat any enthusiasm around incumbent Spanish/European produce suppliers as a potential fade if it is not accompanied by contracted volumes: expanded supplier access can compress farmgate margins before it raises export revenues.
More News
- Saudi, Turkish, Pakistani chiefs plan urgent talks amid Yemen fighting
- Trump Versus Xi: How Their High-Stakes Summits Compare
- Trump, Xi Address AI, Taiwan During State Visit
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- China's Xi urges U.S. to cooperate on AI
- Akamai secures $11.6B cloud deal with Anthropic for AI workloads