
/C O R R E C T I O N -- Rivet/
Source: PR Newswire
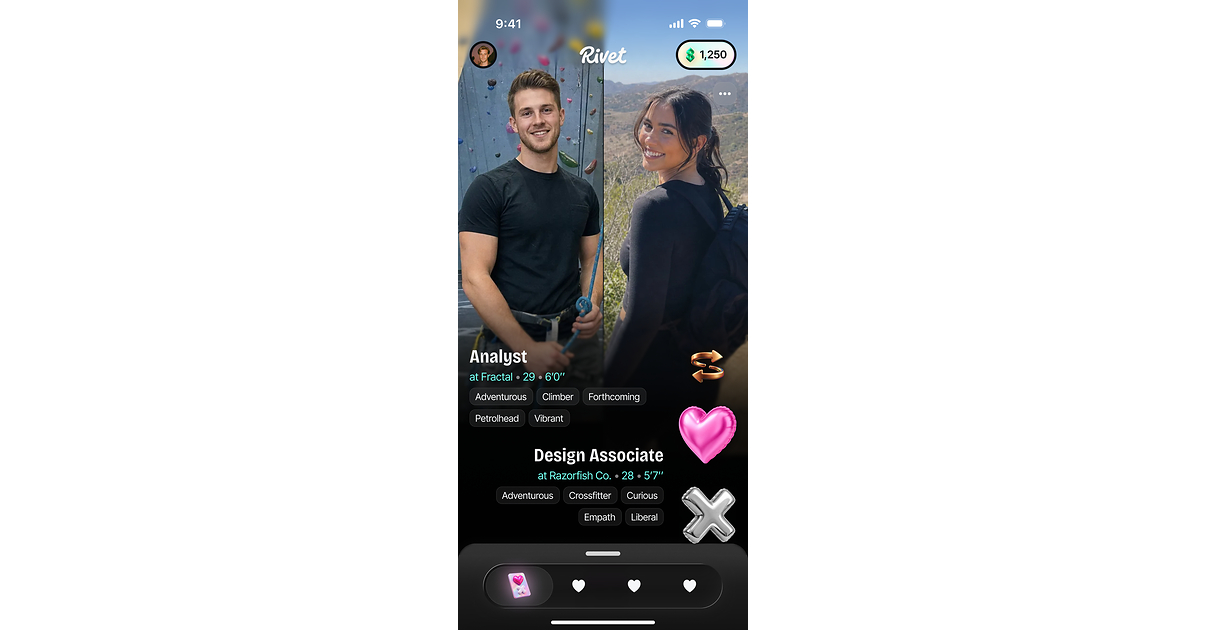
Rivet launched its social-matching dating network nationwide in the U.S. after raising $10.5 million in seed financing from Peak XV Partners, Shine Capital and Blume Ventures. Founded by former Tinder and Match Group executive Taru Kapoor, the platform uses community members' judgments to recommend potential matches rather than relying solely on swipe-based discovery. A Rivet-commissioned survey found 68% of surveyed Gen Z and Millennials would anonymously help unknown people find romantic matches.
Analysis
Rivet is not a near-term revenue threat to Match Group, but it targets the category’s most vulnerable point: declining user willingness to pay for high-volume, low-conviction discovery. A human-curated model could improve match quality and retention if it solves the cold-start problem, but it also substitutes unpaid community labor for the engagement loops that underpin paid boosts, subscriptions and advertising. The more immediate MTCH implication is narrative and multiple-related: another former Tinder executive funding a differentiated entrant reinforces investor concern that swipe mechanics are mature rather than defensible.
The central execution constraint is liquidity, not product novelty. Social matching requires enough active singles, plus a separate pool of motivated matchers, in each local cohort; nationwide availability risks thin local density and poor first-session outcomes. A $10.5m seed round is unlikely to fund sustained consumer acquisition at national scale, so the relevant 1-3 month evidence is App Store ranking, download velocity, daily-active-user retention and city-level density—not commissioned stated-interest surveys.
Contrarian view: Rivet may ultimately validate rather than disrupt incumbents. MTCH has the distribution, identity/safety infrastructure and brand portfolio to copy community-assisted introductions if early retention data prove compelling; a small private entrant may therefore be a product R&D signal, not a share-loss event. The 6-18 month risk to MTCH rises only if Rivet demonstrates materially lower acquisition cost and superior 90/180-day retention in major metros, creating a credible network-effect wedge before Match can replicate the format.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.50
Ticker Sentiment
Key Decisions for Investors
- No standalone MTCH short on this launch; impact is insufficient versus MTCH’s broader payer, pricing and margin drivers. Treat Rivet as a qualitative negative for sentiment, not an earnings estimate change.
- Set a 1-3 month watchlist for Rivet iOS/Android category rank, estimated downloads, reviews and evidence of concentrated traction in New York, Los Angeles and other dense metros. Escalate to a bearish MTCH thesis only if Rivet sustains top-20 Lifestyle/Grossing momentum alongside credible retention disclosures.
- For existing MTCH longs, require upcoming quarterly payer and direct-revenue guidance to offset category-disruption risk. A renewed sequential payer decline or weaker-than-guided monetization would be the catalyst to reduce exposure; stable payer trends would falsify the near-term competitive concern.
- Monitor whether MTCH introduces social referral, friend-assisted matching or curated-introduction features within 6-12 months. Fast feature replication would support a long MTCH-on-weakness view; failure to respond while Rivet gains measurable traction would favor a MTCH underweight versus BMBL.
More News
- Key AI chip index just broke its long-term trendline. What history says happens next
- Banks, investors grow wary of AI debt, spooked by market selloff
- Eli Lilly’s Foundayo obesity pill eases sleep apnea in late-stage trial, paving way for approval
- Musk says Tesla will refund some Cybertruck deposits, defends decision to end production
- Why is Nvidia’s Jensen Huang at the centre of a US-China spy scandal?
- CoreWeave confronts 'doom cycle' narrative as neocloud credit risk overshadows growth