
Huawei Unveils Six Global Power Showcases, Unlocking a New Power System with AI-Energy Synergy
Source: PR Newswire
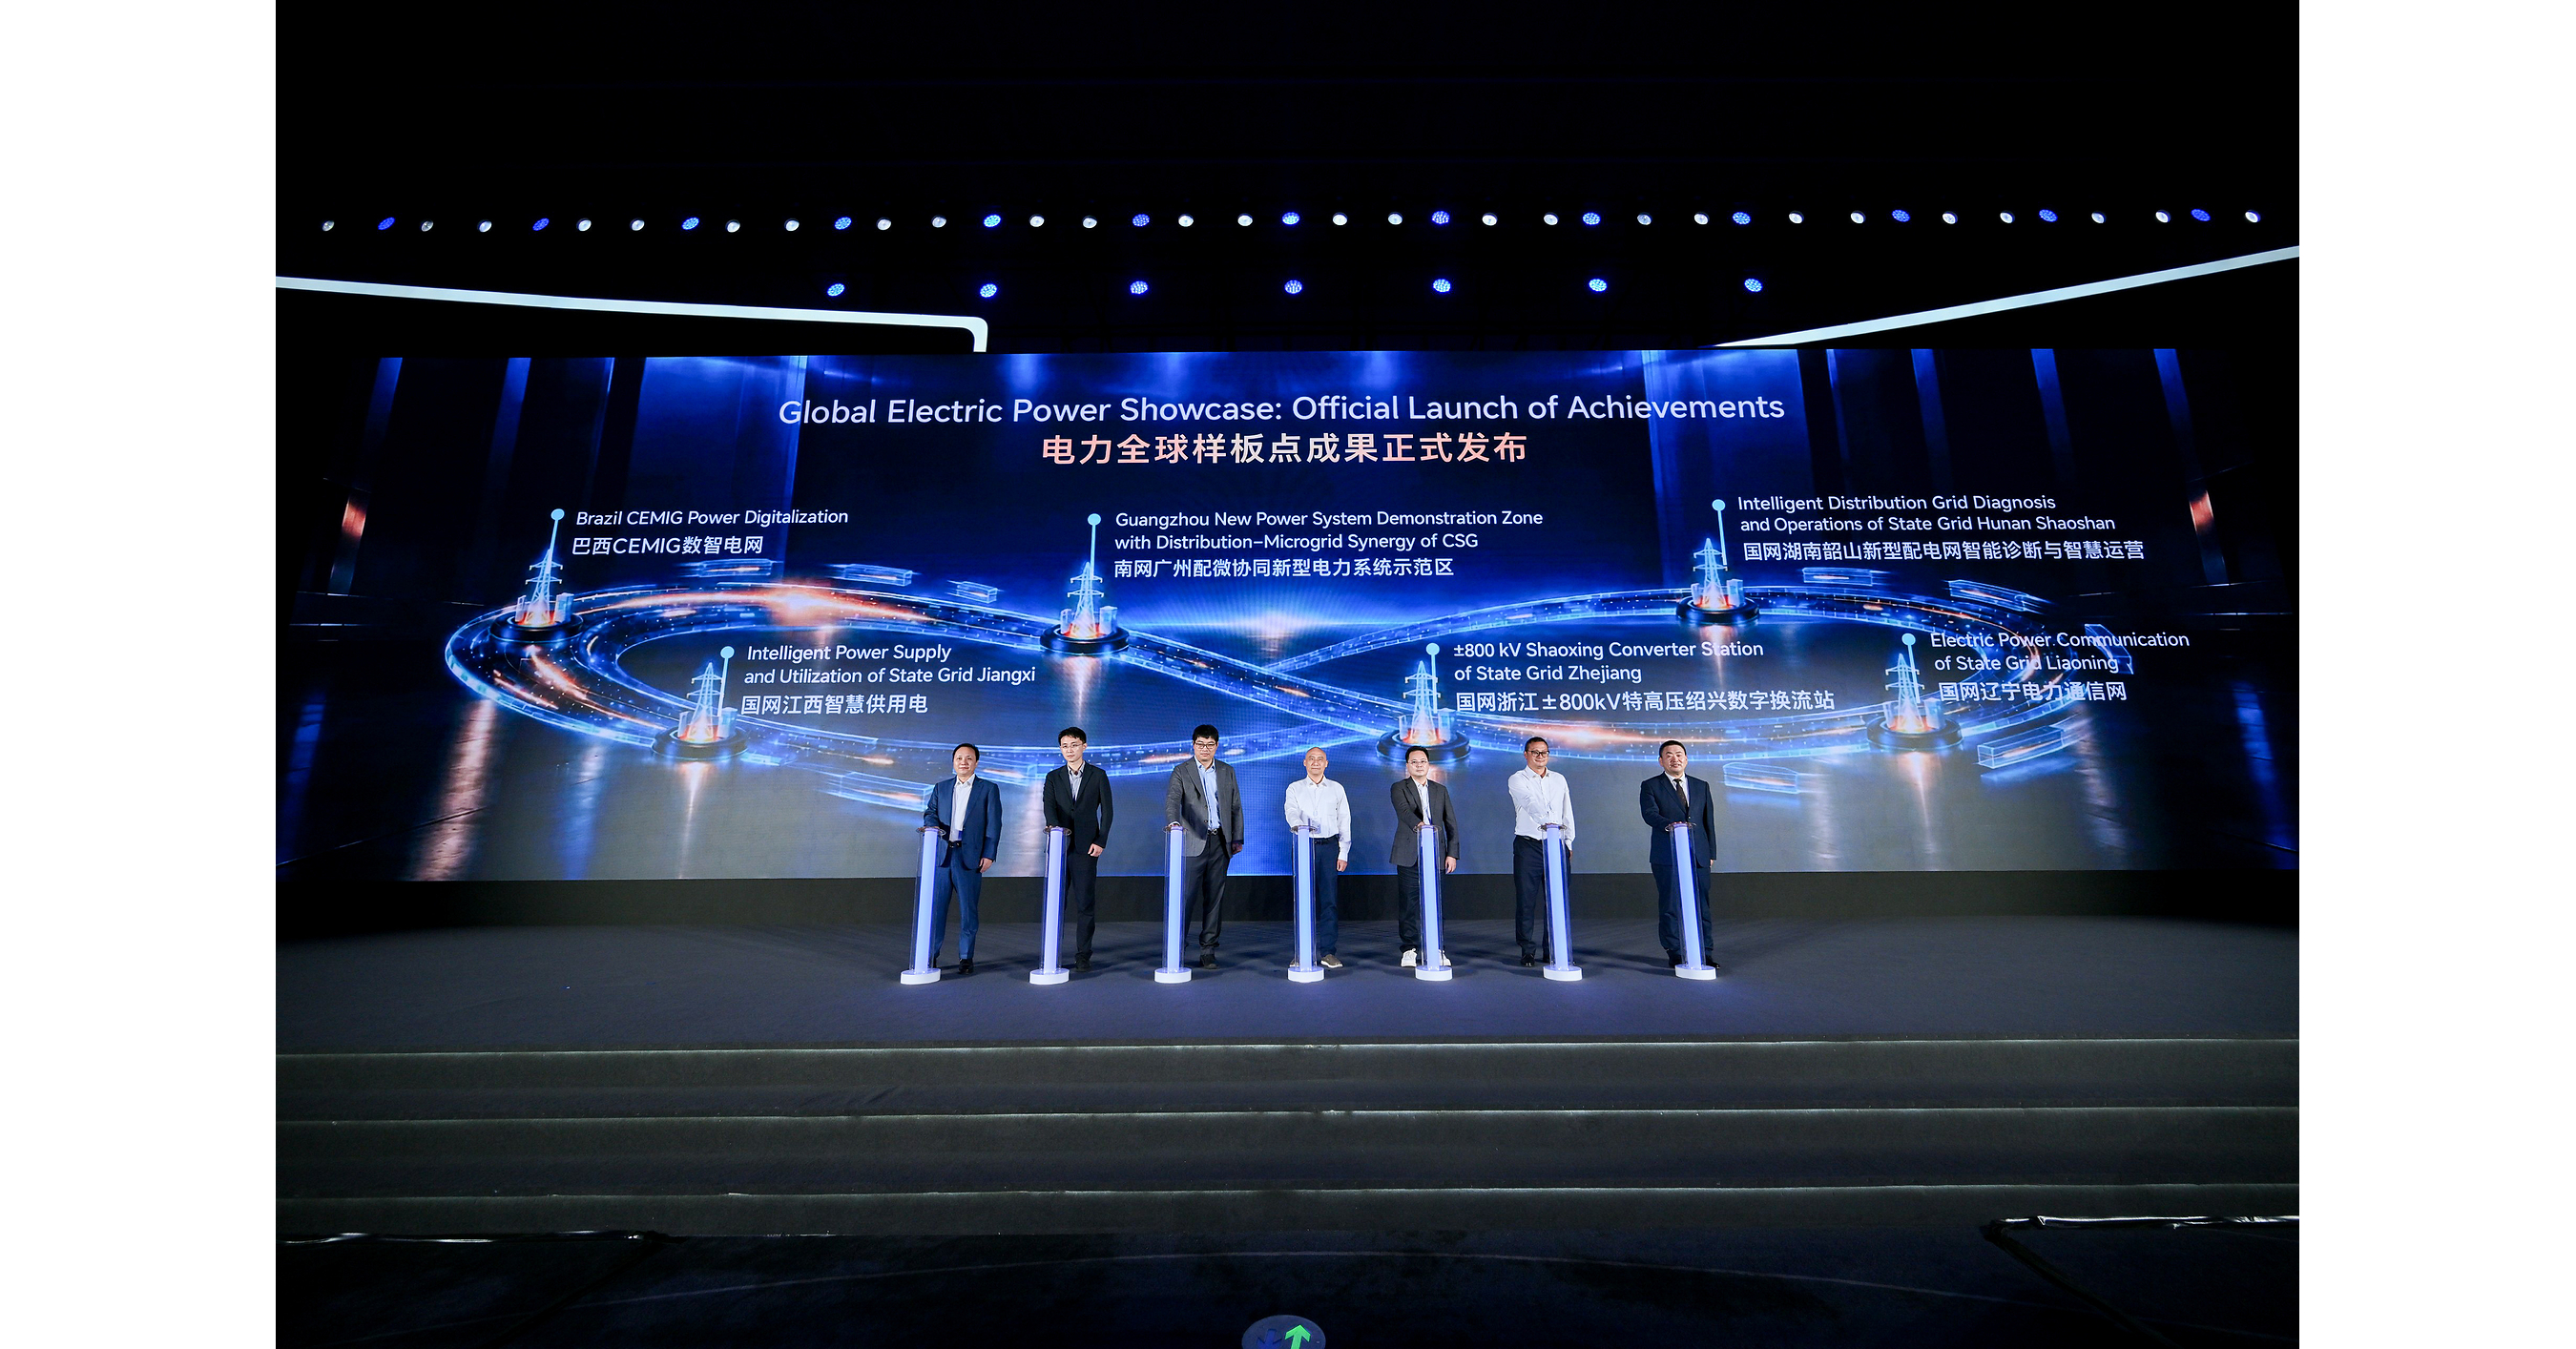
Huawei unveiled six global digital-power showcases at HUAWEI CONNECT 2026, spanning grids, microgrids, power distribution, ultra-high-voltage conversion and communications networks in China and Brazil. The company is positioning AI-enabled low-voltage-grid management as central to integrating distributed renewables, improving resilience and expanding electricity access, while citing 700 million people globally without power access. The announcement highlights Huawei's ICT-led energy infrastructure strategy but provides no financial commitments, contract values, or near-term earnings implications.
Analysis
This is not a Huawei revenue catalyst in isolation; the investable implication is that distribution-grid visibility is becoming a prerequisite for connecting both intermittent generation and AI data-center load. The highest-quality beneficiaries are vendors with installed-base access to utility control rooms and low-/medium-voltage equipment: Eaton (ETN), Schneider Electric (SU.PA), ABB (ABBN.SW), Hubbell (HUBB), Itron (ITRI), and Landis+Gyr (LAND.SW). Their revenue sensitivity is strongest in software-attached hardware, where grid modernization can lift service mix and reduce cyclicality versus pure electrical-component sales.
The second-order effect is competitive fragmentation by geography. Huawei can be a credible low-cost systems competitor in China, emerging markets, and parts of Latin America, potentially pressuring overseas tender pricing; conversely, cybersecurity, procurement restrictions, and data-sovereignty concerns should protect or expand Western vendors' addressable share in North America, Europe, and allied markets. This is structurally more favorable for ETN/HUBB in physical grid hardening and ITRI in metering/data layers than for broad renewable developers, whose economics remain constrained by interconnection queues and power-price volatility.
Near term, the release alone is insufficient to alter estimates or justify a directional position. Over 1-3 months, watch utility capex plans, tender awards, and AI-data-center interconnection disclosures for evidence that distribution automation budgets are moving from pilot programs into regulated rate base; 6-18 month upside depends on regulators allowing accelerated recovery for digital-grid investments. The thesis is falsified if utility capital plans prioritize transmission-only spending, if data-center load growth moderates, or if competitive bids reveal material margin compression in automation equipment.
Consensus may be over-focused on hyperscaler power procurement and high-voltage transmission. The potentially underappreciated bottleneck is distribution equipment and measurement/control software, where load forecasting, dynamic pricing, and demand response can defer expensive physical upgrades. That said, the sector already embeds substantial AI-power demand optimism, so new exposure should be added on procurement evidence or valuation pullbacks rather than on conference announcements.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No immediate Huawei-linked trade: treat this as an alert until named utility contracts, contract values, or regulated-capex commitments are disclosed; the press-release signal is too weak for a standalone position.
- Maintain a 6-18 month overweight in ETN and HUBB versus the broad industrials ETF (XLI): both have direct exposure to distribution upgrades and data-center electrical infrastructure. Add on a 10-15% pullback or after quarterly orders confirm backlog conversion; reassess if organic electrical growth falls below mid-single digits or margins contract on pricing.
- Watch-list ITRI and LAND.SW for a 1-3 month catalyst trade around utility AMI/DERMS awards. Initiate only if bookings/backlog acceleration is visible, as smaller-cap meter vendors face greater tender lumpiness and price competition than ETN/HUBB.
- Consider a relative-value long ETN / short a renewable-heavy proxy such as TAN only if grid-constrained renewable curtailment rises while utility distribution capex is revised upward. The payoff is a shift from generation-capex enthusiasm toward regulated grid-enablement spending; exit if renewable policy support or transmission approvals accelerate materially.
More News
- Saudi, Turkish, Pakistani chiefs plan urgent talks amid Yemen fighting
- Trump Versus Xi: How Their High-Stakes Summits Compare
- SEBI Allows Portfolio Managers to Invest Overseas, Short Equity Options
- Trump, Xi Address AI, Taiwan During State Visit
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- China's Xi urges U.S. to cooperate on AI