
UK Sticks With North Sea Windfall Tax Despite Industry Outcry
Source: Bloomberg
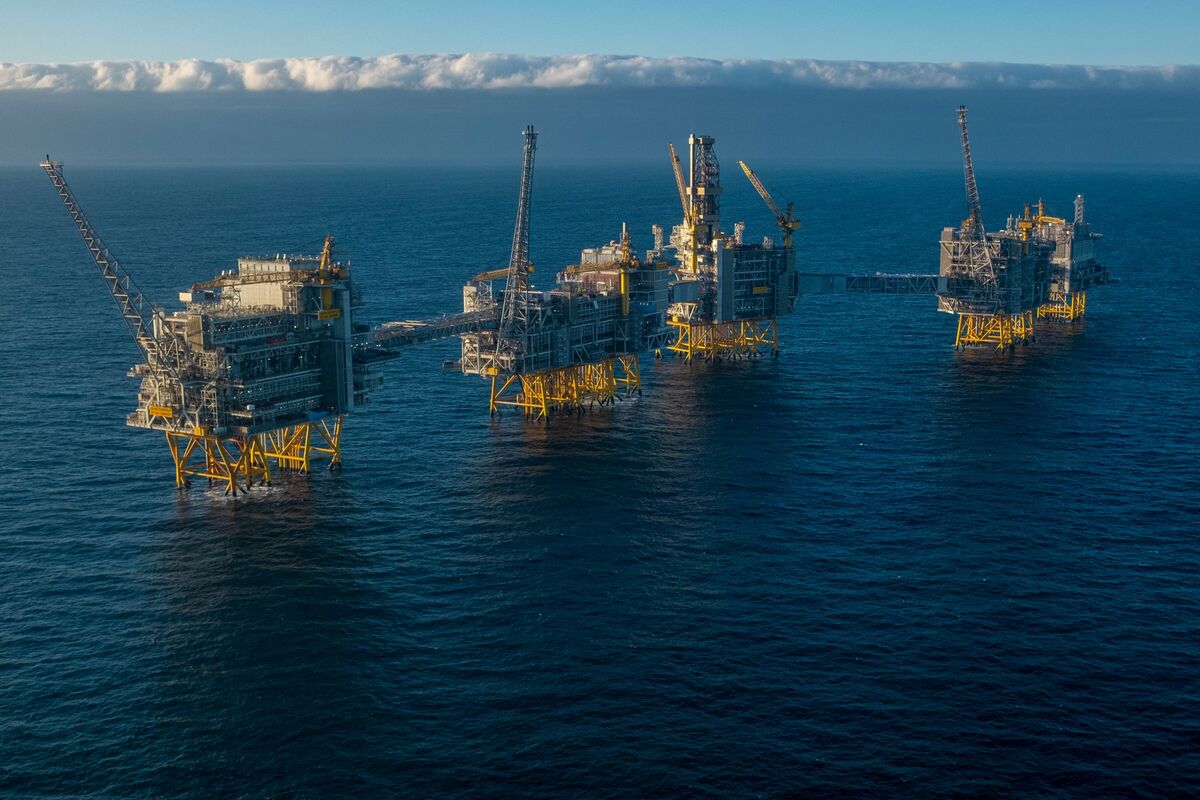
The UK will keep its 38% Energy Profits Levy on North Sea oil and gas producers until April 1, 2030, or earlier if a price floor is triggered, despite industry calls to end it next year. A permanent price-activated tax mechanism is planned to replace the levy when it expires.
Analysis
The key market effect is not simply a higher tax bill: a long-dated, price-linked tax regime raises the hurdle rate for incremental UKCS projects and can redirect capital toward jurisdictions with more predictable fiscal terms. Over 6–18 months, that could mean deferred investment, faster basin decline and fewer future tiebacks—supporting service providers only if other regions absorb the displaced spending, not automatically.
The relative exposure matters more than the headline tax rate. UKCS-focused producers are more vulnerable to reduced project economics than diversified international majors, while their suppliers face a second-order risk if operators cut or postpone activity. A tax regime that captures more upside may also make UK production less responsive when prices rise, potentially increasing future reliance on imports; that is a slow-burn energy-security risk, not an immediate supply shock.
Near term, this is a policy certainty signal but not enough on its own to justify a broad energy short: market reaction depends on what was priced and on each producer’s UK earnings, investment allowances and hedging. The contrarian point is that an earlier exit tied to a price floor may limit downside in weak-price conditions; the larger uncertainty is how the replacement mechanism treats investment and high-price periods. Reassess if project approvals, UKCS capex or company production guidance weaken, or if the tax-floor terms materially improve economics.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.35
Key Decisions for Investors
- Prefer a relative-value watch on UKCS-focused producers versus diversified international energy companies, rather than a sector-wide short. Establish exposure only after comparing UK earnings contribution, tax paid, hedges and project pipeline; those company-level details are not supplied here.
- Avoid chasing an immediate move on the announcement alone. Over the next 1–3 months, monitor producer guidance, sanctioned project economics and UKCS capex plans for evidence that capital is being deferred or redirected.
- Treat oilfield-service names with UK exposure as a conditional downside watch, not an automatic short: the thesis requires UK activity reductions that are not offset by stronger spending elsewhere. Falsify it if UK contract awards and activity remain resilient.
- Track the detailed price-floor and successor-tax rules. A credible investment allowance or a lower effective burden at relevant price levels could reverse the bearish project-economics view; weaker UK production guidance or cancellations would strengthen it.
More News
- Budget 2026 speech
- GE Vernova shares slip despite a beat-and-raise. What the sellers are getting wrong
- Asian shares fall as Alphabet earnings miss drags Wall St futures lower
- Burnham’s government unveils its first UK budget: What to expect
- Alphabet Disappoints as Microsoft’s Cloud Brightens
- Trump methane policy rollback may have minimal impact on crude prices, EPA says