
DISNEY BRINGS THE MAGIC OF DISNEY'S LAKESHORE LODGE TO NEW YORK CITY
Source: PR Newswire
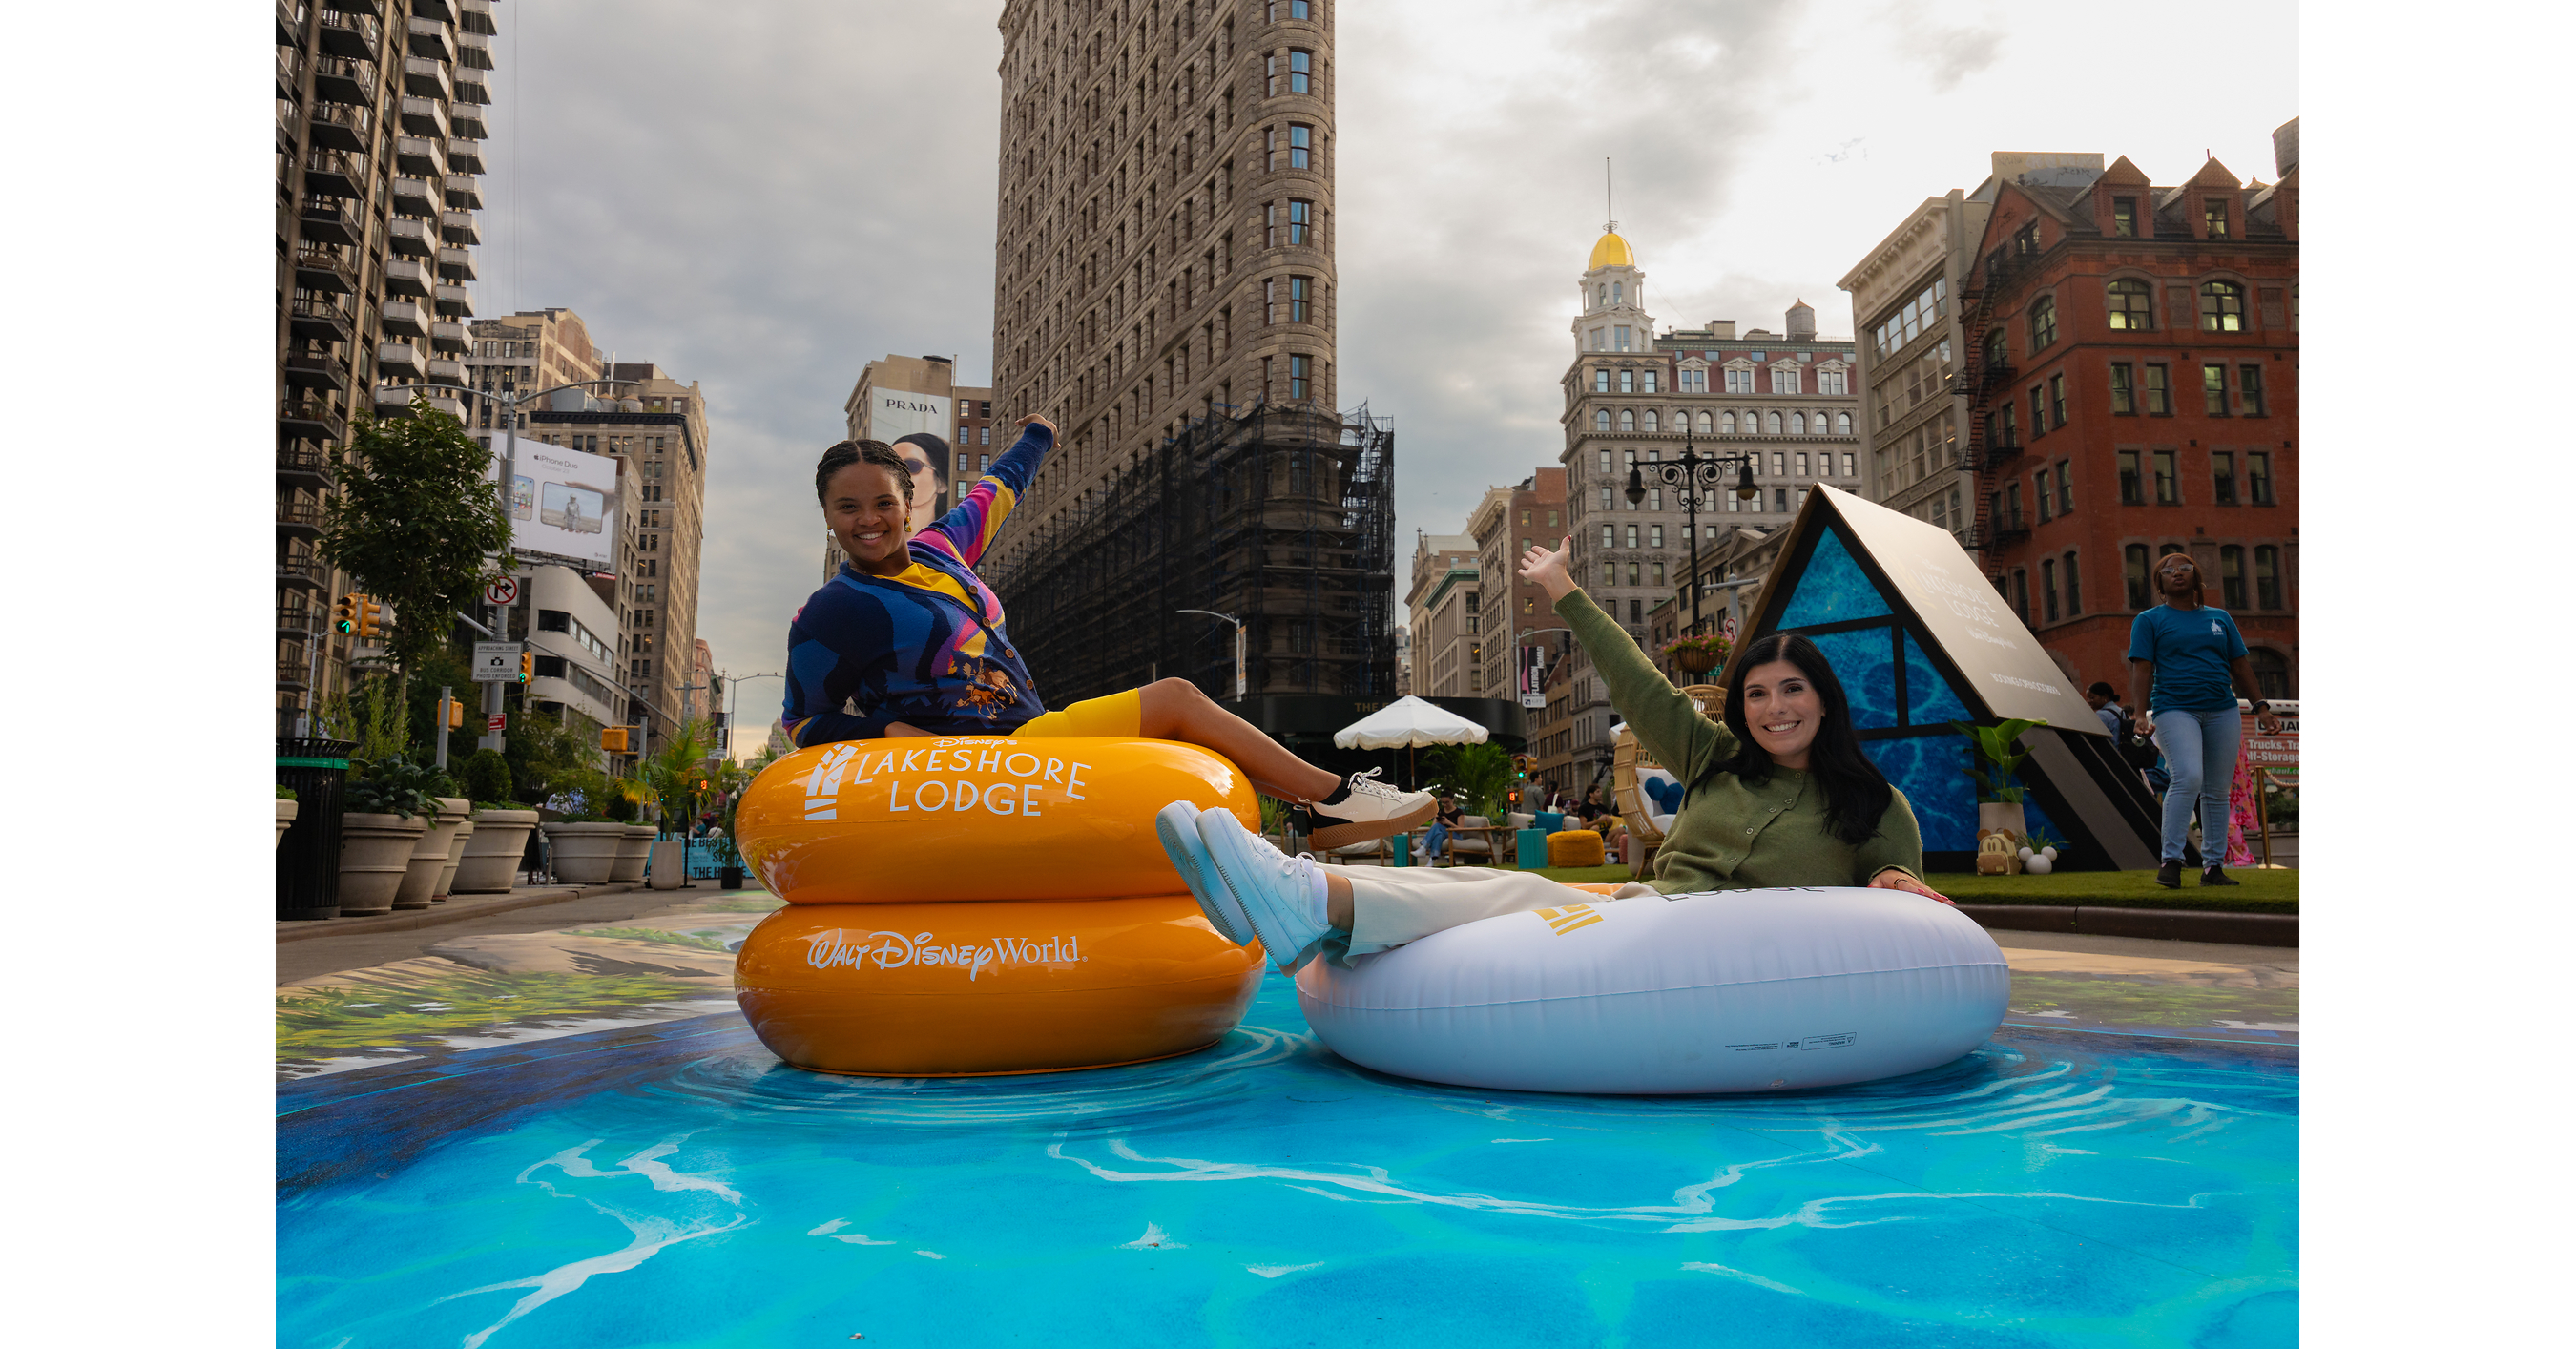
Disney Experiences promoted Disney's Lakeshore Lodge, a 967-room Walt Disney World waterfront resort scheduled to open July 1, 2027, through a one-day 3D mural activation in New York. Disney Vacation Club members, annual passholders and the general public can begin booking from Oct. 6, Oct. 7 and Oct. 8, respectively. The announcement supports Disney's long-term parks and resorts offering but provides no financial guidance, pricing, or expected attendance impact.
Analysis
This is not a near-term DIS earnings catalyst: even under a $400-$500 blended ADR and 80%-85% occupancy assumption, a 967-key property contributes only roughly $110-$150M of annual lodging revenue, with EBITDA sensitivity likely below $50M before accounting for the vacation-club ownership mix. The investable issue is whether the asset raises per-guest monetization and length of stay rather than simply displacing demand from Disney's existing deluxe inventory. A high proportion of villa and vacation-club inventory would improve upfront cash generation and reduce cyclicality, but also makes reported hotel-revenue contribution materially less transparent.
The more relevant 6-18 month read-through is capital-allocation credibility in Experiences: new on-property capacity can capture lodging spend currently leaking to Orlando peers, while proximity to the highest-demand park should support premium pricing if attendance remains capacity-constrained. Conversely, if the property requires discounting to fill, it would signal that domestic visitation elasticity is deteriorating and could pressure resort-wide RevPAR rather than create incremental demand. Consensus is unlikely to move estimates on this announcement alone; any share-price reaction should be viewed as narrative-driven unless management quantifies incremental DVC sales, occupancy, ADR, or segment return targets.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No standalone DIS trade on this release; the implied earnings contribution is too small relative to segment and corporate-estimate noise.
- Maintain DIS as a watch item into the next Experiences update: initiate or add only if management indicates on-property occupancy/RevPAR growth without incremental discounting and provides evidence that new inventory is demand-accretive rather than cannibalistic.
- Monitor Disney Vacation Club disclosures and deferred-revenue/cash-flow commentary through the July 2027 opening. A stronger-than-expected ownership mix and pre-sales pace would be incrementally positive for cash conversion; weak pre-sales would undermine the premium-resort demand thesis.
- Falsification trigger: sustained resort promotional activity or a meaningful downgrade to domestic park/resort growth guidance over the next 1-3 quarters would indicate the added capacity is entering a softer demand environment, warranting reduced DIS exposure.
More News
- Disney licenses lineup of movies, TV shows to Netflix including ’Ice Age,’ ’Will Trent’
- Paramount and Warner Bros. Discovery to Merge Into Skydance (SKYD). Will Skydance Achieve David Ellison’s "Quality Storytelling" Vision?
- Disney lays off around 300 employees as D'Amaro pushes cost cuts
- Your health insurance premiums may take a big jump in 2027 — here's why
- Why Lilly and Novo are betting on amylin to power a new wave of obesity drugs after GLP-1s
- Nike falls to 13-year low. Why analysts don't think the selling is over yet
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Hebbia Alternatives: A Workflow-Based Buyer’s Guide
- 2026 Global Markets Outlook: Asset Allocation After the Great Disconnect