
Stryker introduces first of its kind FDA-authorized surgical application for Apple Vision Pro with hip arthroscopy case at nationally recognized academic medical center
Source: PR Newswire
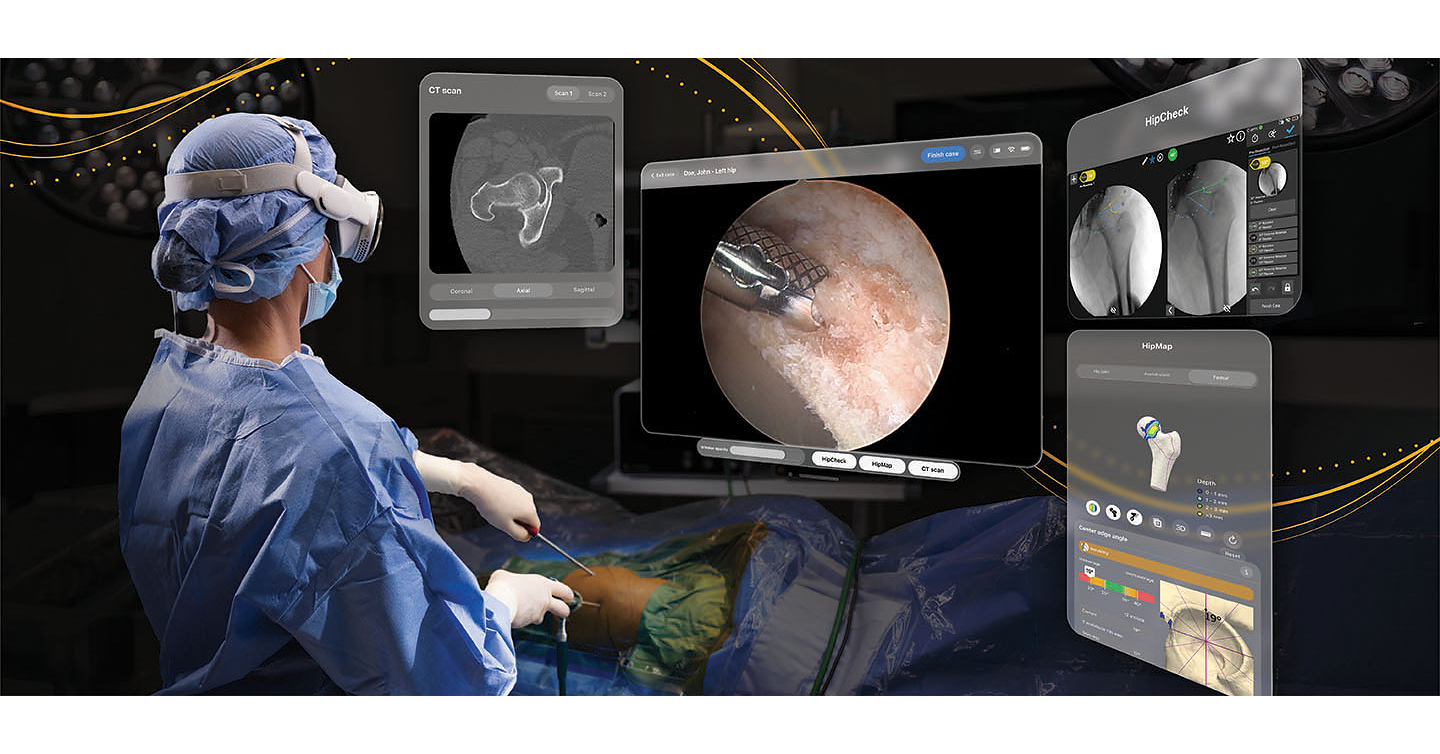
Stryker (SYK) completed the first surgical procedure using SportSuite Vision on Apple Vision Pro at Duke Health (hip arthroscopy), following FDA De Novo authorization on July 17 for intraoperative use. The system integrates arthroscopic video plus HipCheck, HipMap, and CT imaging into a customizable spatial computing workspace to reduce reliance on multiple OR monitors and streamline workflow. While this is an important regulatory and product milestone for digital surgery/spatial computing, the article provides no financial impact or guidance, suggesting modest near-term market relevance.
Analysis
This is a branding and workflow win for SYK more than an immediate earnings event. The important mechanism is not incremental hardware revenue from a single procedure; it is that Stryker is starting to wrap its orthopedic software, imaging, and procedural workflow into a sticky surgeon-facing interface, which can raise attach rates to its broader sports medicine franchise and improve win rates in capital decisions over the next 6-18 months. The near-term market reaction should be modest because hospitals buy proof of reproducibility, not demos; adoption will depend on whether this reduces OR time, errors, or training burden enough to justify workflow change.
The second-order winner is AAPL as a platform credibility story in regulated enterprise settings, but the financial impact is likely immaterial until there is evidence of broader hospital IT integration and repeatable deployment across specialties. A more important competitive implication is for other medtech names with weaker digital surgery narratives: JNJ, MDT, and smaller orthopedic workflow vendors may need to answer on software differentiation, though this is more about multiple support than revenue displacement. The main risk is that spatial computing remains a niche accessory constrained by ergonomics, sterility protocols, and surgeon preference, in which case the product becomes a press-release feature rather than a commercial wedge.
Consensus may be underestimating the option value of first-mover regulatory approval: if Stryker can show measurable time savings or better visualization, this can become a sales amplifier for premium procedure bundles and a defense against commoditization in orthopedics. But the thesis fails if additional sites do not follow within 1-2 quarters, or if surgeons revert to standard monitors after novelty wears off. For AAPL, this is a watch item, not a thesis driver, unless we see a pipeline of FDA-cleared clinical apps that turns Vision Pro into a real enterprise platform.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Modestly long SYK on any post-news pullback over the next 1-2 weeks; the trade is for 6-18 month multiple support from digital surgery optionality, not immediate EPS accretion. Risk/reward is favorable if management later quantifies workflow gains, but keep sizing small because this is still pre-scale.
- Watch for a relative-value long SYK / short MDT or JNJ basket over 1-3 months if Stryker starts talking about additional clinical modules or hospital rollouts. The edge is narrative and sales-force leverage, not patent moat.
- Do not chase AAPL on this headline alone; treat it as a monitoring item for a broader regulated-enterprise platform thesis. Reassess only if additional FDA-cleared medical applications emerge within 2-3 quarters.
- Set a catalyst alert on SYK for evidence of multi-site adoption, OR time reduction, or procedural throughput metrics over the next 1-2 quarters; absent that, fade the enthusiasm.
- If SYK underperforms despite follow-on adoption signals, consider a short-term call spread only after confirmation, because the stock already trades with quality-premium expectations and the market may have priced some of the story.
More News
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’
- TSMC chip capacity is ‘fierce’ battleground for AI customers, amid record quarter
- Can TSMC earnings help settle AI jitters?
- Apple and Meta team up to make Muse AI model run on Mac computers
- Smartphone shipments plummet as memory crisis pumps up prices
- Nvidia’s European spending spree is about much more than Europe
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- The $4.7 Trillion Bet: When Does AI Capex Become AI Revenue?
- Equity Research Automation Statistics: A 2026 Evidence Check