
SANY Renewable Energy meldet auf der WindEnergy Hamburg 2026 ein Wachstum des Auslandsumsatzes von über 300 %
Source: PR Newswire
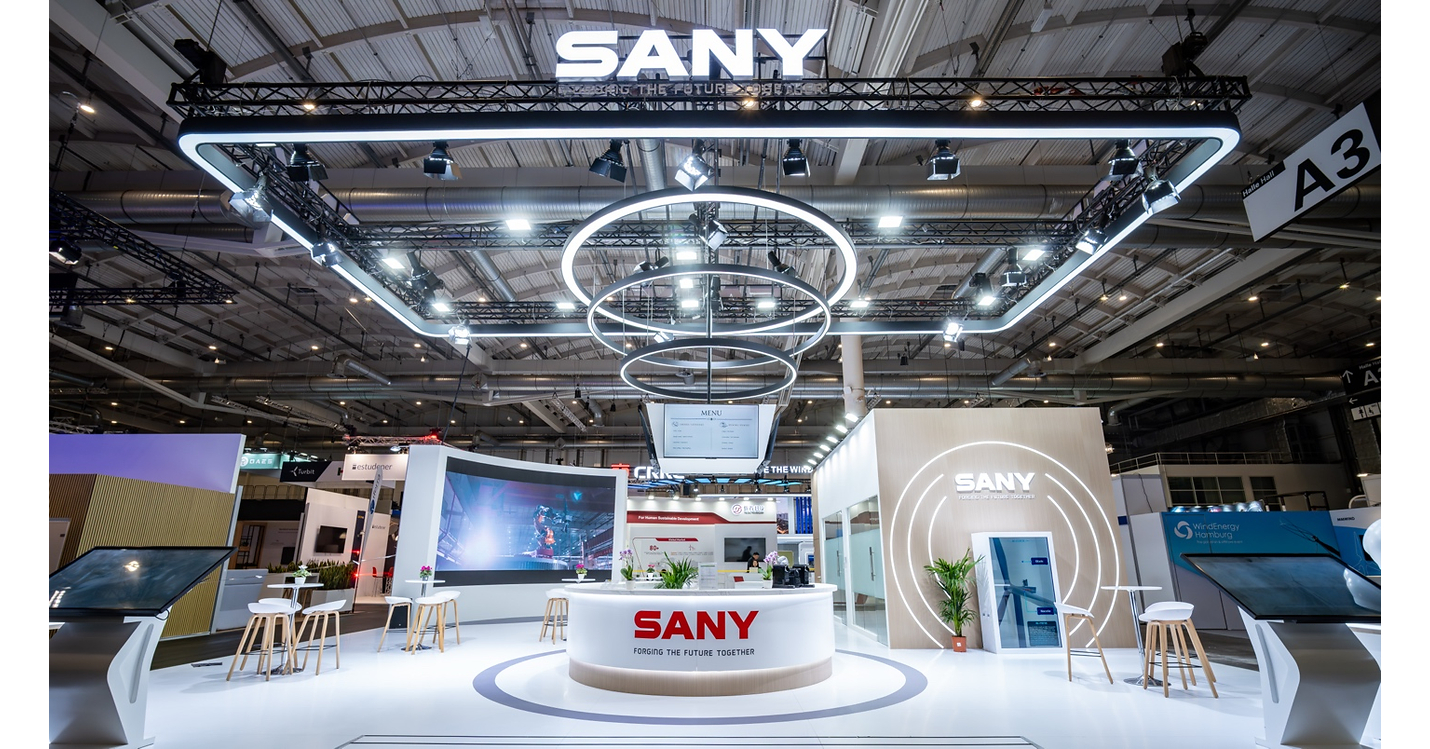
SANY Renewable Energy reported overseas revenue growth of more than 300% in H1 2026 and nearly 5 GW of signed international orders, underscoring rapid global expansion. DNV awarded European certification for SANY's SI-17578EU turbine, supporting entry into European markets, while overseas installed capacity reached 1,462.35 MW. The company highlighted 10-MW turbine technology, AI-enabled blade-clearance modeling and a 35-MW test bench as it pursues international growth in wind power.
Analysis
The investable implication is less about SPGI and more about whether another Chinese OEM can convert technical qualification into financed European installations. If SANY Renewable (688349.SS) establishes a credible European service footprint, it could widen the low-cost competitive set facing Vestas (VWS.CO), Nordex (NDX1.DE), and Siemens Energy (ENR.DE). The first-order effect is likely tender-price pressure; the more important 6-18 month effect is higher warranty, local-parts, and working-capital requirements for entrants, which can limit the apparent cost advantage unless project-finance lenders accept long-dated availability guarantees.
The reported order momentum should not be valued as equivalent to revenue backlog until disclosed by geography, cancellation terms, deposits, and financing status. Large-turbine contracts commonly carry 12-30 month conversion cycles, while European permitting, grid queues, and trade-policy scrutiny can delay recognition materially. For incumbents, a renewed Chinese OEM challenge is negative for future pricing but may be offset near term by European customers' preference for bankable service contracts; VWS and ENR's installed-base service economics are more defensible than new-equipment gross margin.
The contrarian view is that certification is a commercial door-opener, not proof of European bankability or profitable scale. EU foreign-subsidy investigations, local-content procurement rules, cybersecurity requirements, and lender reluctance to underwrite an unproven regional O&M record could make penetration slower than headline contract announcements imply. SPGI has no material earnings sensitivity: a supplier-ranking or sustainability-assessment reference is not a reason to trade the stock.
Over the next 1-3 months, monitor European tender wins, disclosed turbine ASPs, local manufacturing/service investment, and named financing partners. A sequence of financed projects with independent availability data would validate competitive pressure; conversely, contract deferrals, elevated warranty provisions, or EU procurement exclusions would falsify the entrant thesis.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- No directional SPGI trade: the referenced assessment has immaterial revenue or margin linkage. Treat any article-driven move as noise unless management identifies a paid data, ratings, or index-product contribution.
- Maintain a 6-12 month watchlist short thesis on European wind OEM new-build margin exposure, particularly VWS.CO and NDX1.DE, but do not initiate solely on this release. Trigger only if two or more European tenders show Chinese OEM awards at materially lower disclosed pricing and incumbents reduce EBIT-margin guidance; cover on evidence that procurement restrictions exclude Chinese suppliers.
- Prefer ENR.DE over pure-play turbine OEMs on a relative basis over 6-18 months: installed-base service and grid-equipment exposure provide a partial hedge against turbine pricing pressure. Risk to the relative trade is a broad European wind buildout accelerating new-turbine volumes enough to offset price compression.
- For China-capable investors, monitor 688349.SS rather than chase a headline: consider long exposure only after verification of overseas backlog conversion, customer deposits, and service-capex commitments in results. The key risk/reward hinge is whether overseas gross margin exceeds domestic margin after warranty and localization costs; absent that disclosure, this remains an alert, not a recommendation.
More News
- AMC Entertainment stockholders approve equity plan amendment, reject board changes
- Treasury yields continue to rise after 10-year hit 19-year high as investors ramp-up rate hike bets
- Japan approval, a 27% surge: the diagnostics stock our models picked in September
- Trump Versus Xi: How Their High-Stakes Summits Compare
- Trump, Xi Address AI, Taiwan During State Visit
- China's Xi urges U.S. to cooperate on AI