
Corgi Insurance Appoints Daniel Oldham as Head of Underwriting for Trucking
Source: PR Newswire
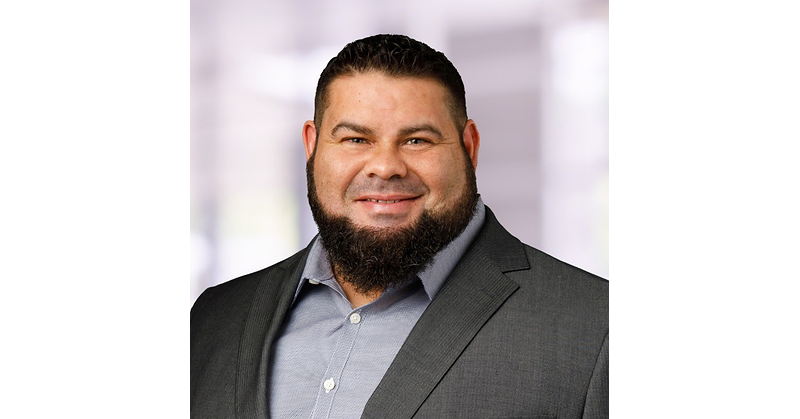
Corgi Insurance appointed Daniel Oldham as Head of Underwriting for Trucking, where he will oversee risk selection, pricing, portfolio management, product development, and broker relationships. At his prior employer, Canopius Group, Oldham grew the transportation book from $10 million to $39 million while maintaining underwriting profitability. The appointment supports Corgi’s stated effort to expand its trucking business, but the announcement provides no financial results or quantified outlook for Corgi.
Analysis
This is a capability signal, not yet an earnings signal. The potential advantage is better risk selection, pricing and broker conversion in a difficult trucking line; the counter-risk is that premium growth can destroy value if claims severity, repair costs, litigation or driver-risk trends outrun pricing. A senior hire’s prior results do not establish that those outcomes transfer to Corgi’s data, capacity or distribution. Canopius and other specialty carriers could face some talent or broker competition, but the announcement alone does not imply a material change to their portfolios.
Near term (days), little tradeable information is disclosed. Over 1–3 months, look for evidence of broker appointments, program launches and underwriting capacity. Over 6–18 months, the differentiator would be persistently profitable growth through a trucking claims cycle—not premium expansion alone. Key missing checks are Corgi’s underwriting capacity and reinsurance arrangements, state/product availability, written premium, loss and expense ratios, and claims development. A deterioration in commercial-auto loss trends or constrained reinsurance could overwhelm improved underwriting processes.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No direct position is warranted from this announcement: Corgi has no supplied ticker, and the release provides no independently verifiable financial impact.
- Treat this as a watch item for private-market diligence: request evidence of capacity, reinsurance support, broker distribution and loss-ratio performance before underwriting a growth thesis.
- For publicly traded commercial insurers or brokers with trucking exposure, avoid trading on presumed share loss to Corgi; revisit only if Corgi demonstrates scaled distribution or a measurable shift in pricing and renewal retention.
- Falsify the positive operating thesis if reported trucking premium growth is accompanied by worsening loss ratios, adverse claims development, or reduced capacity; evidence of profitable renewal growth would strengthen it.
More News
- Qatar Reinvents LNG Trade to Restore Global Clout Even as Iran War Drags
- Why is Domino’s Pizza Enterprises stock sliding today?
- South Korean carmaker Hyundai plans 'strategic' investment of $15.5 billion in India by 2032
- Airport attacks put aviation in crosshairs of geopolitical conflicts
- Applied Materials’ $5 billion AI lab aims to cut chip development time in half—and restore Silicon Valley’s edge
- Wells Fargo CFO on Earnings, Deals, Consumer Strength
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Is an AI Investment Research Platform?
- What Exactly Does Post-Training in LLMs and Finance-Focused AI Actually Mean for Asset Managers?