
Pantum Technology présente ses nouvelles solutions d'impression à l'IFA 2026 et renforce sa stratégie de développement sur le marché européen
Source: PR Newswire
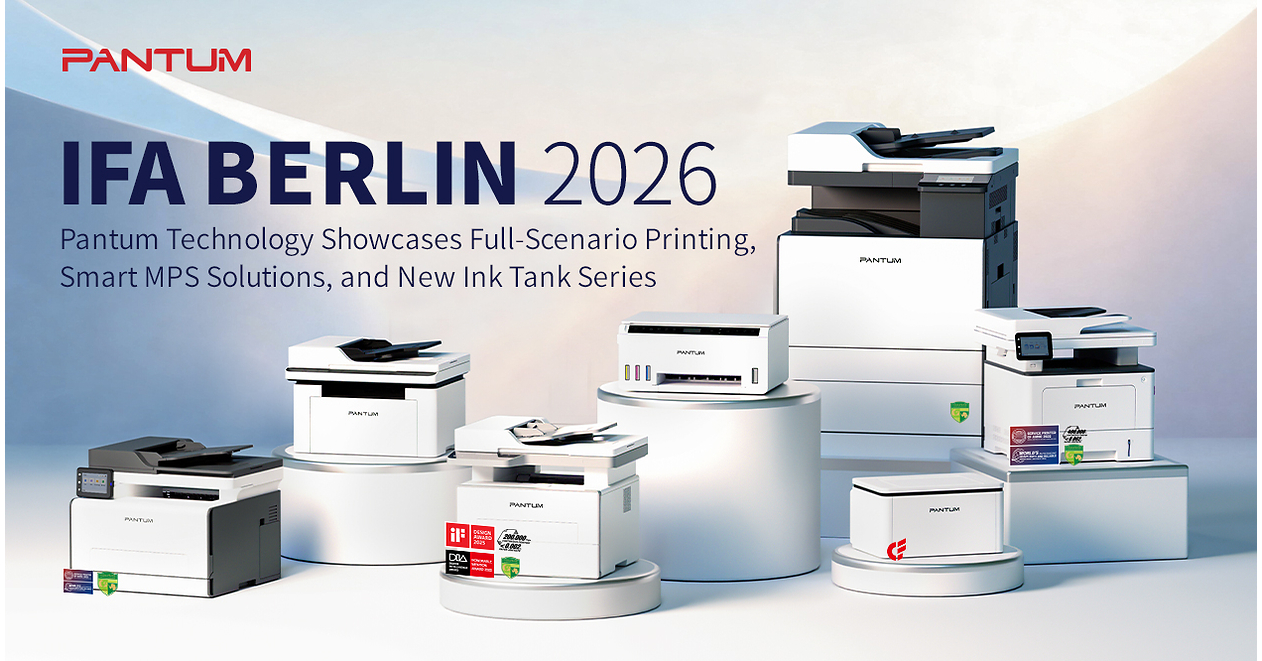
Pantum Technology unveiled new printing products at IFA 2026, led by the AI-enabled BM2320NW and the MT310W continuous-ink-tank printer scheduled for launch in 2027. The company also introduced two A3 color laser models, including the CM420ADN with up to 2,096-sheet input capacity, while expanding its managed print-services ecosystem through PiPME software and partnerships with Docuform, NDD and MyQ. Pantum is strengthening its European strategy with local offices, warehousing, logistics and after-sales operations across a network spanning more than 110 countries and regions.
Analysis
This is not independently actionable for listed equities, but it modestly raises competitive risk for HP Inc. (HPQ), Canon (CAJ), Seiko Epson (SEKEY), Brother Industries (BRTHY), and Ricoh (RICOY) in European entry-level laser and managed-print channels. The principal pressure point is consumables: a low-cost vendor pairing tank-ink economics in home/SMB with locally supported managed-print software can reduce the installed-base lock-in that supports recurring toner revenue and service margins for incumbents.
Near term, the announcement should not affect estimates; the consumer tank product has no near-term revenue relevance and AI-printing claims lack a measurable willingness-to-pay signal. Over 1-3 months, monitor European channel checks, distributor shelf-space changes, and tender wins in public-sector A3 printing, where lower hardware pricing can be used to seed future supplies and service revenue. The higher-value risk emerges over 6-18 months if Pantum demonstrates credible local repair coverage, regulatory compliance, and MPS integration; those are the barriers that have historically protected incumbent enterprise print economics.
The contrarian view is that penetration may remain constrained by buyer concerns around security certification, fleet-management interoperability, and guaranteed consumables availability. Incumbents' installed bases and contractual MPS relationships are durable, so a product-show launch alone does not justify a directional short. The relevant falsifier for the disruption thesis is evidence of European share gains accompanied by declining incumbent supplies revenue or gross-margin guidance, rather than unit growth alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No immediate directional trade; classify as a competitive-intelligence alert rather than an earnings-changing event given the absence of pricing, shipment, European market-share, or customer-contract data.
- Add HPQ and CAJ to European print-channel monitoring for the next two quarters: escalate only if supplies revenue growth decelerates by more than 200 bps year-over-year, gross margin misses guidance, or disclosed European MPS/public-sector losses emerge.
- For existing HPQ longs, consider modest downside hedges into the next earnings date only if channel checks show Pantum discounting in laser consumables or A3 tenders; the risk/reward is otherwise unfavorable because incumbent service revenue is unlikely to move on a single launch cycle.
- Watch Brother (BRTHY) and Ricoh (RICOY) for enterprise-print tender exposure rather than consumer hardware exposure. A sustained Pantum win rate in European public-sector A3 fleets over 6-12 months would support a relative short basket versus diversified office-equipment peers.
More News
- Oil prices jump after Yemen’s Houthis claim attacks on Saudi facilities
- Saudi, Turkish, Pakistani chiefs plan urgent talks amid Yemen fighting
- Oil falls amid optimism over potential diplomatic solution to the Iran conflict
- Trump Versus Xi: How Their High-Stakes Summits Compare
- Trump, Xi Address AI, Taiwan During State Visit
- SEBI Allows Portfolio Managers to Invest Overseas, Short Equity Options
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Can ChatGPT or Claude Replace a Research Platform?
- How the 2026 Milan-Cortina Winter Olympics Will Reshape Company Revenues and Stock Performance