
Congrès mondial de l'industrie manufacturière 2026 : des présentations de produits aux écosystèmes de fabrication intégrés
Source: PR Newswire
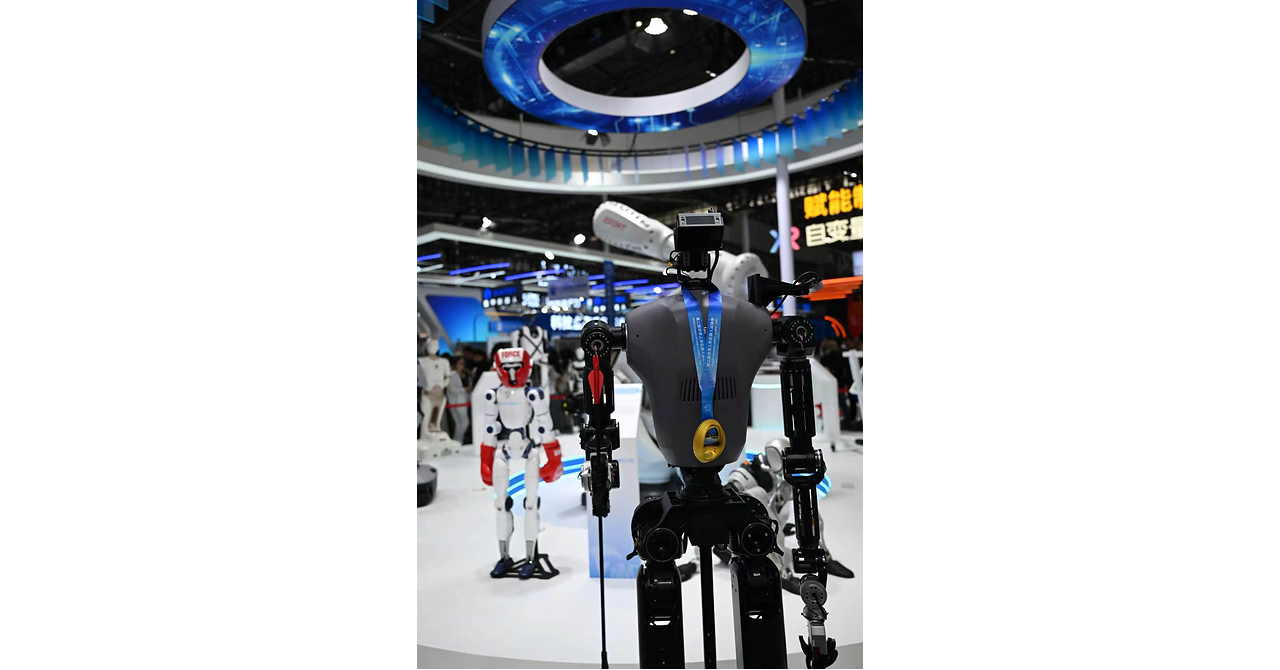
China's 2026 World Manufacturing Convention brought together more than 900 companies, over 10,000 products and technologies, and 70,000 square meters of exhibition space focused on integrated smart-manufacturing ecosystems. Key displays included a 180-qubit superconducting quantum processor, fusion-energy technology, embodied AI, 6G, EV supply-chain systems and intelligent eldercare solutions. Anhui produced 2.0158 million vehicles in the first seven months of 2026, including 1.0903 million EVs, and exported 1.227 million vehicles, underscoring the province's expanding role in China's advanced-manufacturing and EV industries.
Analysis
This is principally a signal of China’s localization push across industrial automation, EV components and AI-linked power infrastructure rather than a near-term earnings event. The likely second-order pressure falls on multinational component suppliers with China manufacturing exposure: domestic substitution can erode pricing and share even if end-market vehicle and automation volumes remain healthy. GLW’s China display operations are more exposed to a gradual mix shift toward local materials and panel-adjacent suppliers than to any immediate demand shock; the relevant risk is lower incremental China revenue and weaker utilization leverage over the next 6-18 months.
CON’s participation highlights the opposite dynamic: foreign suppliers can retain a premium position where qualification cycles, safety certification and OEM validation matter, particularly in tires for exports. But China’s rapidly expanding vehicle export base increases the probability that local OEMs standardize locally sourced components before overseas sales scale, making multinational content-per-vehicle more vulnerable than headline Chinese auto production implies. Watch Chinese EV export policy responses in Europe and tariff changes: restricted exports would redirect capacity into domestic price competition and intensify supplier margin pressure.
The tradable implication is not to chase broad China industrial exposure from a promotional event. The more actionable medium-term theme is a widening dispersion between upstream, globally qualified specialty-component vendors and commoditized suppliers facing local-capacity oversupply. Confirmation requires evidence in quarterly China sales growth, OEM sourcing disclosures and gross-margin commentary—not exhibition announcements.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- Maintain GLW as a watch-list short hedge versus a broader US industrial/technology basket over 3-6 months; initiate only if management guides China Display sales below market expectations or segment margin falls by more than 150bp year-over-year. The falsifier is sustained China volume growth with stable price/mix, which would demonstrate that localization is expanding the addressable market rather than displacing Corning.
- Avoid adding to CON solely on China industrial or EV-export enthusiasm. For existing exposure, monitor China/Asia-Pacific organic revenue and replacement-tire pricing at the next two earnings prints; a 200bp-plus gross-margin deterioration alongside flat volume would support reducing exposure.
- Use a 6-12 month relative-value screen rather than a directional trade: favor companies with proprietary, qualified exposure to AI power-grid equipment and high-voltage components over broad China EV supply-chain proxies. Require order backlog, pricing realization and export-market data before taking a position.
- Set an event alert for EU trade measures on Chinese EVs and for Chinese auto-export monthly data. A material export slowdown is bearish for China-linked component volumes but potentially bullish for global incumbent suppliers if it reduces low-cost competition in their core markets.
More News
- Saudi, Turkish, Pakistani chiefs plan urgent talks amid Yemen fighting
- Oil falls amid optimism over potential diplomatic solution to the Iran conflict
- Trump Versus Xi: How Their High-Stakes Summits Compare
- SEBI Allows Portfolio Managers to Invest Overseas, Short Equity Options
- Trump, Xi Address AI, Taiwan During State Visit
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: New Reporting Features and More Sources for Document Search
- How to Evaluate AI Report Writers for Financial Analysis