
Pantum Technology predstavuje na veľtrhu IFA 2026 nové tlačové riešenia -rozšírenie stratégie pre európsky trh
Source: PR Newswire
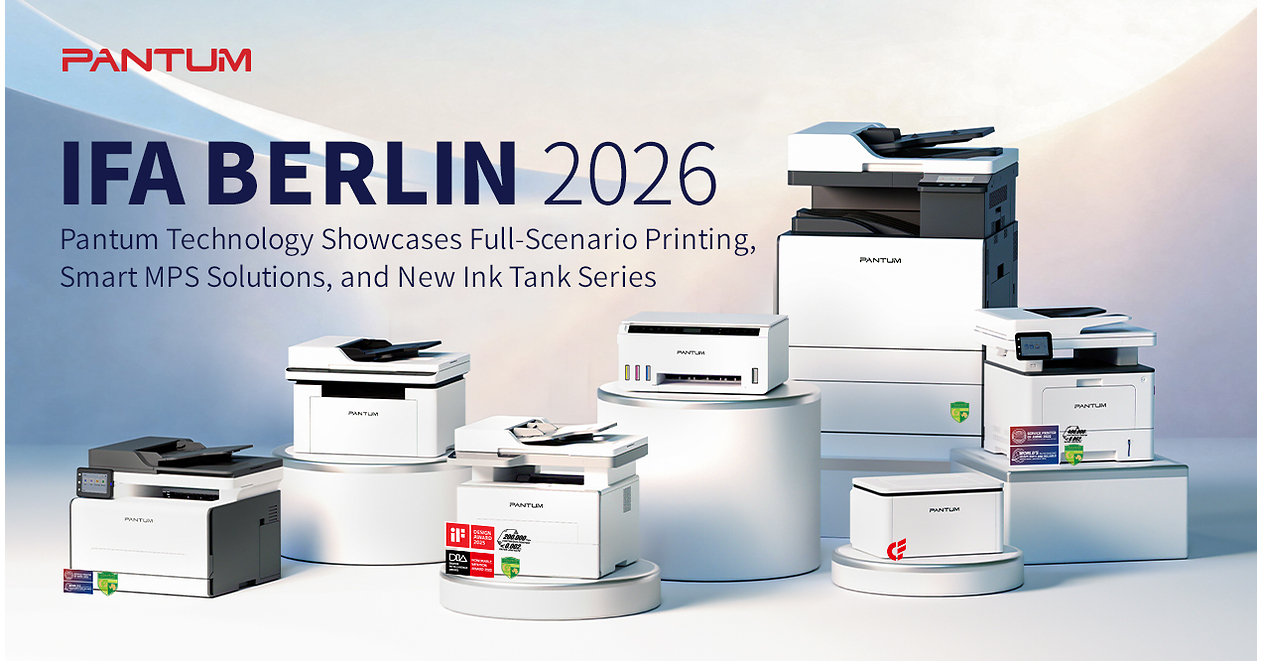
Pantum Technology unveiled new printing products at IFA 2026, including the MT310W ink-tank printer planned for launch in 2027 and the AI-enabled BM2320NW printer, currently available only in mainland China. The company also introduced two A3 color laser models for enterprise and institutional users, with the CM420ADN supporting up to 2,096 sheets of input capacity. Pantum is expanding its European strategy through local warehousing, logistics and after-sales teams, while extending managed-printing partnerships and software capabilities.
Analysis
This is not currently a listed-equity catalyst: Pantum is privately held and the release provides no pricing, unit-volume, channel-win, or consumables-attach data needed to translate new products into earnings. The strategic implication is nonetheless mildly negative at the margin for HP Inc. (HPQ), Canon (CAJ) and Seiko Epson (SEICY): a lower-cost entrant expanding European distribution can pressure entry-level A4 hardware pricing, where OEMs often accept low device margins to protect recurring toner/ink pools.
The more material competitive threat is not the consumer ink-tank device but Pantum's effort to combine A3 laser hardware, fleet-management software and local service. If it wins European managed-print contracts, incumbents face a two-stage risk over 6-18 months: initial tender-price compression followed by consumables and service revenue leakage. However, enterprise switching costs, security certifications, dealer incentives and installed-base workflow integration remain substantial barriers; trade claims around AI functionality have no independently demonstrated monetization value.
Near term, this should be treated as a channel-check signal rather than a trade trigger. Monitor 1-3 month European reseller listings, tender awards, pricing versus comparable HP/Canon/Brother devices, and any evidence that Pantum has secured public-sector certifications. A broad price move in HPQ, CAJ or SEICY on this release alone would likely be overdone because Pantum's European revenue and share trajectory are undisclosed.
The contrarian view is that aggressive low-end competition can be more damaging to smaller regional printer dealers and third-party consumables vendors than to OEMs with contractual enterprise fleets. HPQ's greater risk is concentrated in consumer/SMB print hardware and supplies, while Canon's diversified imaging and industrial earnings base should dilute any impact; this supports a relative, not outright, expression if verifiable share-loss evidence emerges.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.34
Key Decisions for Investors
- No immediate directional position; place HPQ, CAJ and SEICY on a European channel-monitor list for the next 90 days. Require evidence of Pantum retail shelf placement, MPS tender wins or material price undercutting before acting.
- Conditional pair trade over a 6-12 month horizon: short HPQ / long CAJ if HPQ reports EMEA print hardware unit declines or supplies-margin pressure while Canon maintains office-print guidance. Target 8-12% relative return; exit if HPQ sustains supplies revenue growth above guidance or Pantum distribution evidence fails to emerge.
- For existing HPQ longs, scrutinize quarterly supplies revenue, print-segment operating margin and EMEA hardware ASPs rather than shipment growth alone. A 100-150 bp segment-margin deterioration tied to competitive pricing would be a stronger thesis confirmation than product-launch headlines.
- Avoid assigning value to the AI-printing feature until there is disclosed software subscription, service revenue, or enterprise adoption data. Treat an AI-driven valuation rerating for printer OEM peers as unsupported by current evidence.
More News
- Saudi, Turkish, Pakistani chiefs plan urgent talks amid Yemen fighting
- Oil falls amid optimism over potential diplomatic solution to the Iran conflict
- Trump Versus Xi: How Their High-Stakes Summits Compare
- SEBI Allows Portfolio Managers to Invest Overseas, Short Equity Options
- Trump, Xi Address AI, Taiwan During State Visit
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent