
Taiwan Expo USA 2026 Brings Taiwan's AI Infrastructure Ecosystem to Life in Dallas
Source: PR Newswire
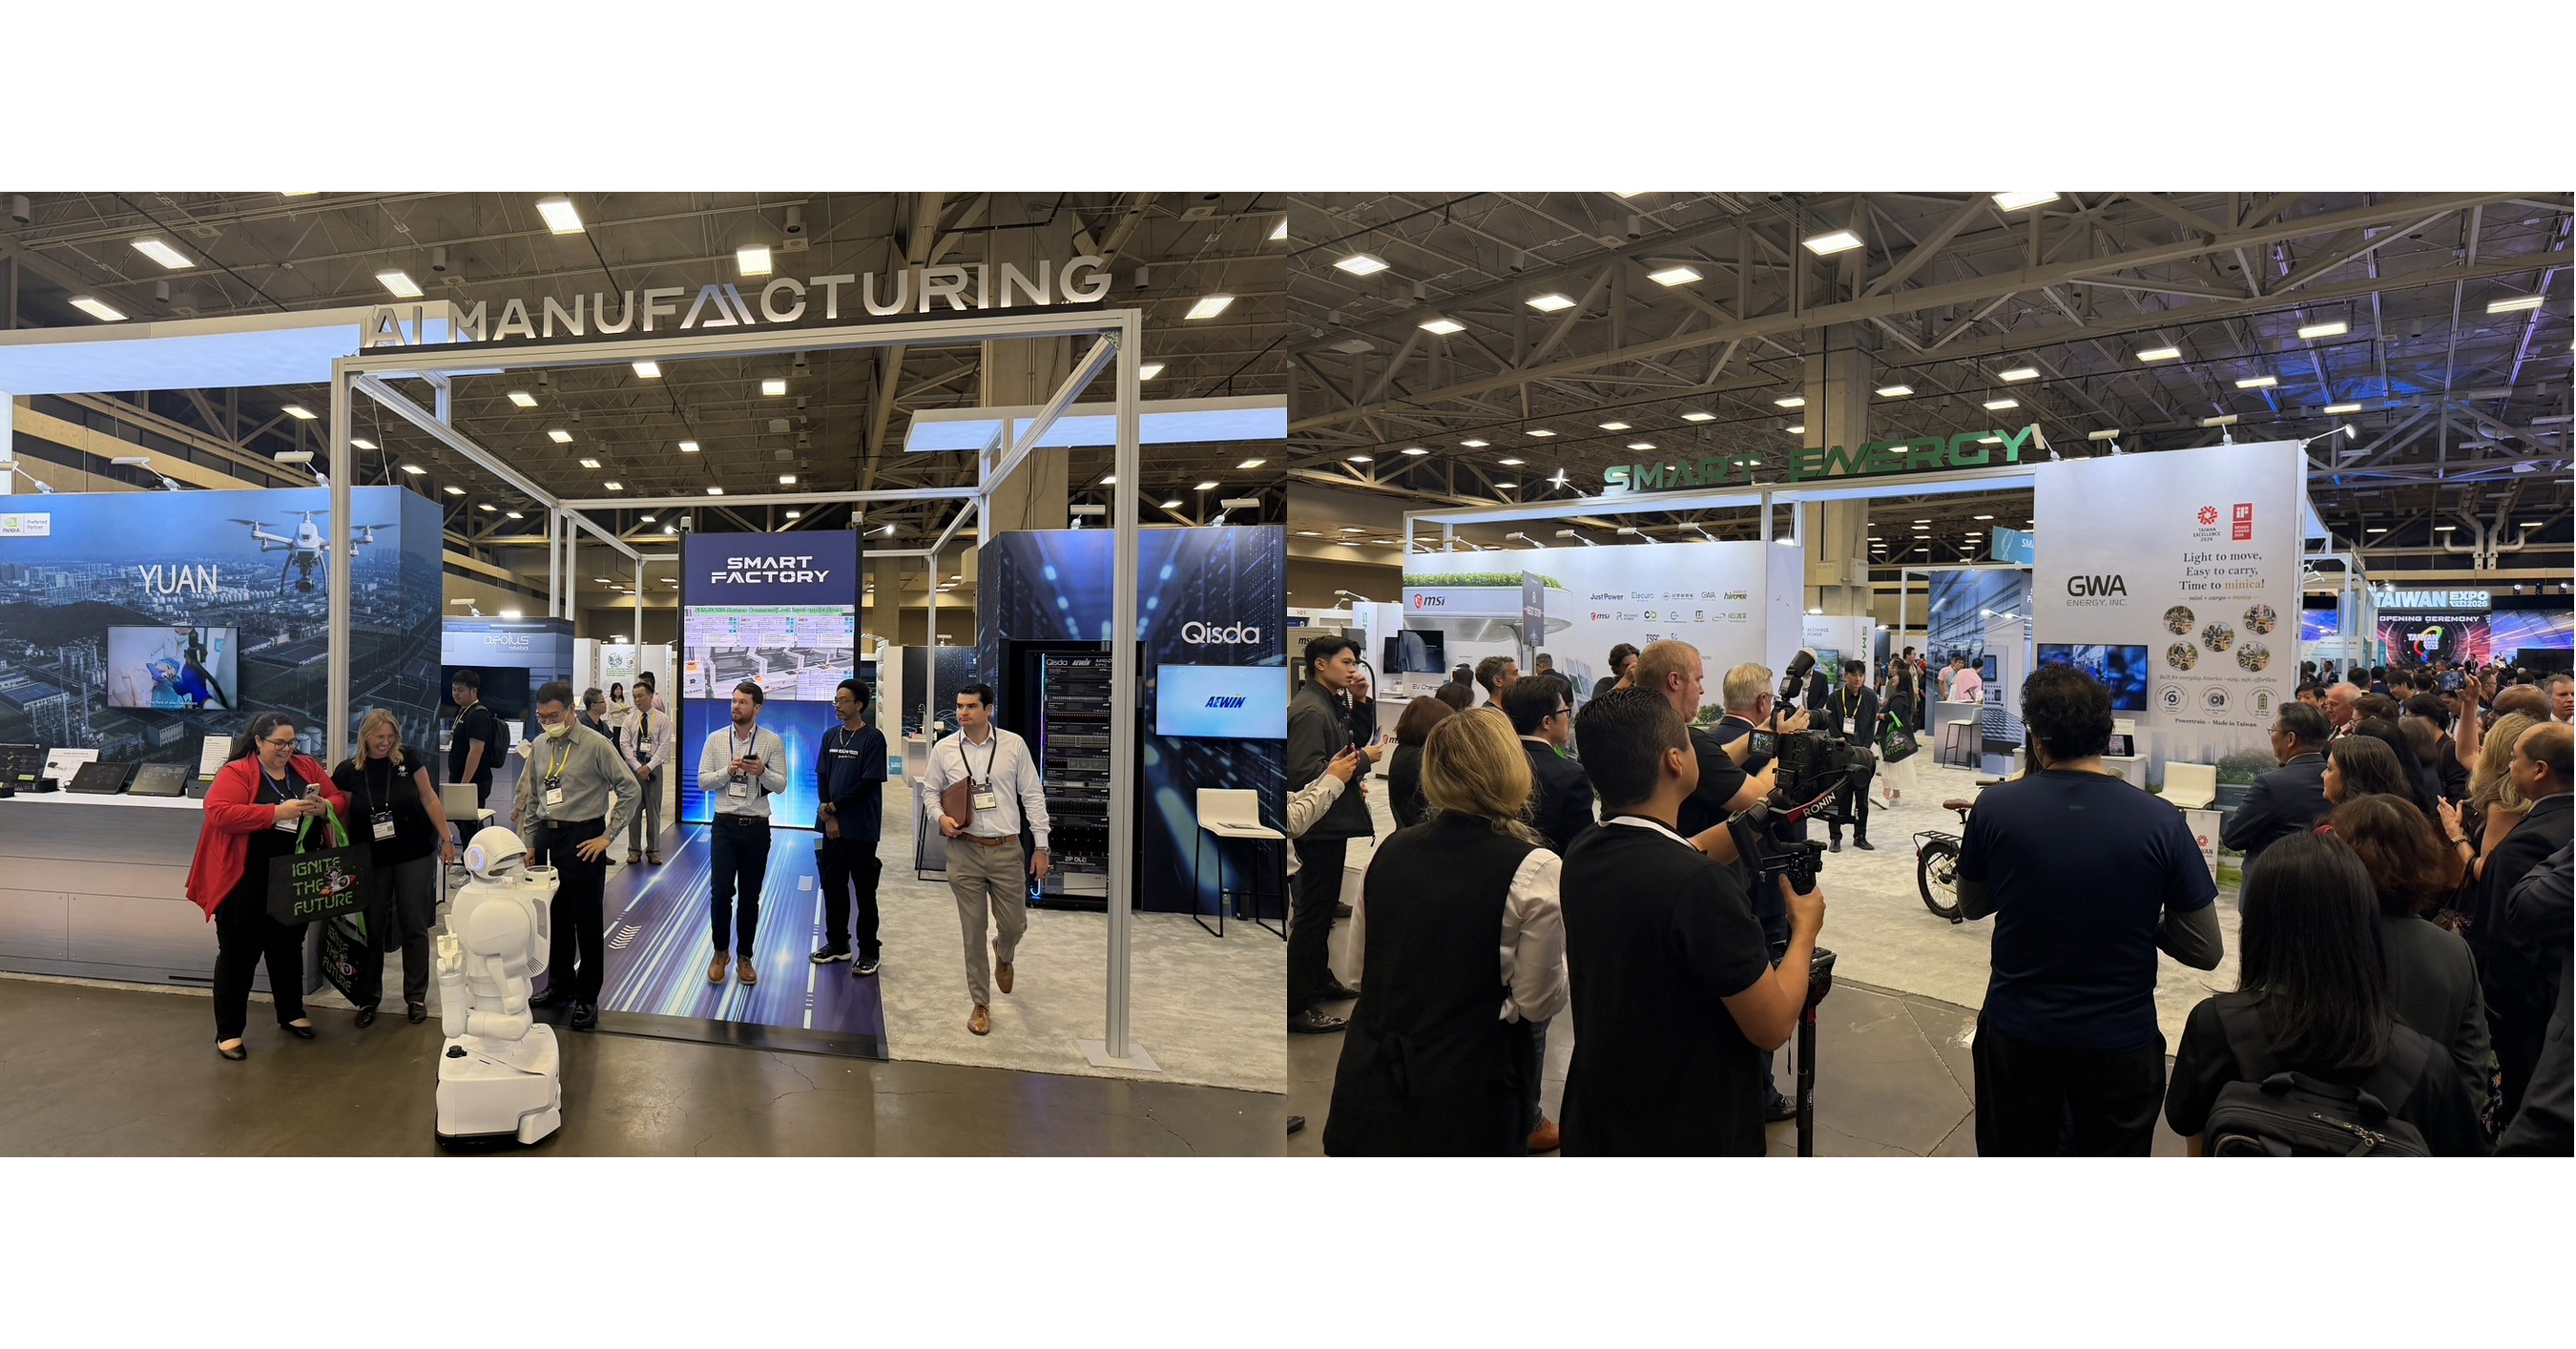
Taiwan Expo USA 2026 opened in Dallas with adjacent AI Manufacturing and Smart Energy pavilions occupying 260 square meters and featuring Taiwanese AI servers, liquid cooling, industrial AI, robotics, energy storage, hydrogen and recycling technologies. The exhibition highlights Taiwan’s end-to-end smart-factory and AI-infrastructure supply-chain capabilities, with reported engagement from major U.S. power-systems and automotive-electronics companies. The September 24–26 event is primarily a trade-promotion showcase and does not disclose material contracts, financial results, or commitments likely to move public markets.
Analysis
This is primarily a supply-chain signaling event rather than a near-term earnings catalyst. The investable implication is that Taiwanese vendors are increasingly positioning around the two binding constraints in AI physical infrastructure: thermal density and power availability. That supports the medium-term revenue pools of liquid-cooling and power-management leaders such as Vertiv (VRT), Eaton (ETN), Schneider Electric (SU.PA), Delta Electronics (2308.TW), and Taiwan’s server ODMs Quanta (2382.TW) and Wiwynn (6669.TW), but an exhibition does not establish purchase commitments or incremental capacity.
The second-order risk is that AI capex bottlenecks migrate from GPUs to grid interconnection, backup power, storage, and cooling-water availability. Over 6-18 months, this favors firms selling power-distribution and thermal systems with qualified installed bases over commoditized server assemblers, whose margin capture can remain constrained despite volume growth. Battery recycling, hydrogen, and photovoltaic recycling exposure should not be extrapolated from product demonstrations: those markets remain far more dependent on subsidy economics, permitting, and utilization rates than on AI data-center demand.
Consensus may be too quick to treat all "AI infrastructure" suppliers as equivalent beneficiaries. A sustained data-center build cycle should widen the relative valuation premium for VRT/ETN versus lower-margin IT hardware integrators, while also increasing execution risk where lead times normalize and hyperscalers shift toward standardized, multi-sourced architectures. No standalone trade is warranted from this release; confirmation requires disclosed U.S. design wins, backlog conversion, and evidence that cooling/power attach rates are rising rather than merely being marketed.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- Maintain a 6-12 month quality bias toward VRT and ETN versus broad AI-hardware exposure: both monetize the power-and-thermal bottleneck with higher service content. Add only on 10-15% pullbacks or after earnings confirm backlog growth and stable gross margin; exit the relative thesis if orders decelerate for two consecutive quarters or pricing compresses.
- Watch long 2382.TW or 6669.TW / short a diversified Taiwan electronics-manufacturing proxy for a 6-18 month pair only if U.S. AI-server order disclosures show accelerating rack-level shipments. The missing data are customer concentration, liquid-cooling content per rack, and U.S. production footprint; absent these, event-driven exposure is unjustified.
- Avoid treating hydrogen, PV recycling, or battery-recycling exhibitors as AI-infrastructure proxies. Reassess only after signed offtake agreements, project-financing disclosures, or policy changes establish revenue visibility; these themes carry materially higher subsidy and execution risk than data-center electrical equipment.
- Set an alert around hyperscaler capex guidance and U.S. utility interconnection timelines over the next 1-3 months. Upward capex revisions with worsening interconnection delays would strengthen VRT/ETN; a broad capex cut or evidence of power-equipment lead-time normalization would be the near-term falsifier.
More News
- Saudi, Turkish, Pakistani chiefs plan urgent talks amid Yemen fighting
- Oil falls amid optimism over potential diplomatic solution to the Iran conflict
- Trump Versus Xi: How Their High-Stakes Summits Compare
- SEBI Allows Portfolio Managers to Invest Overseas, Short Equity Options
- Trump, Xi Address AI, Taiwan During State Visit
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AlphaSense Pricing: What Public Contract Data Shows in 2026
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market