
China’s Gold Imports Top 1,000 Tons on Strong Investment Demand
Source: Bloomberg
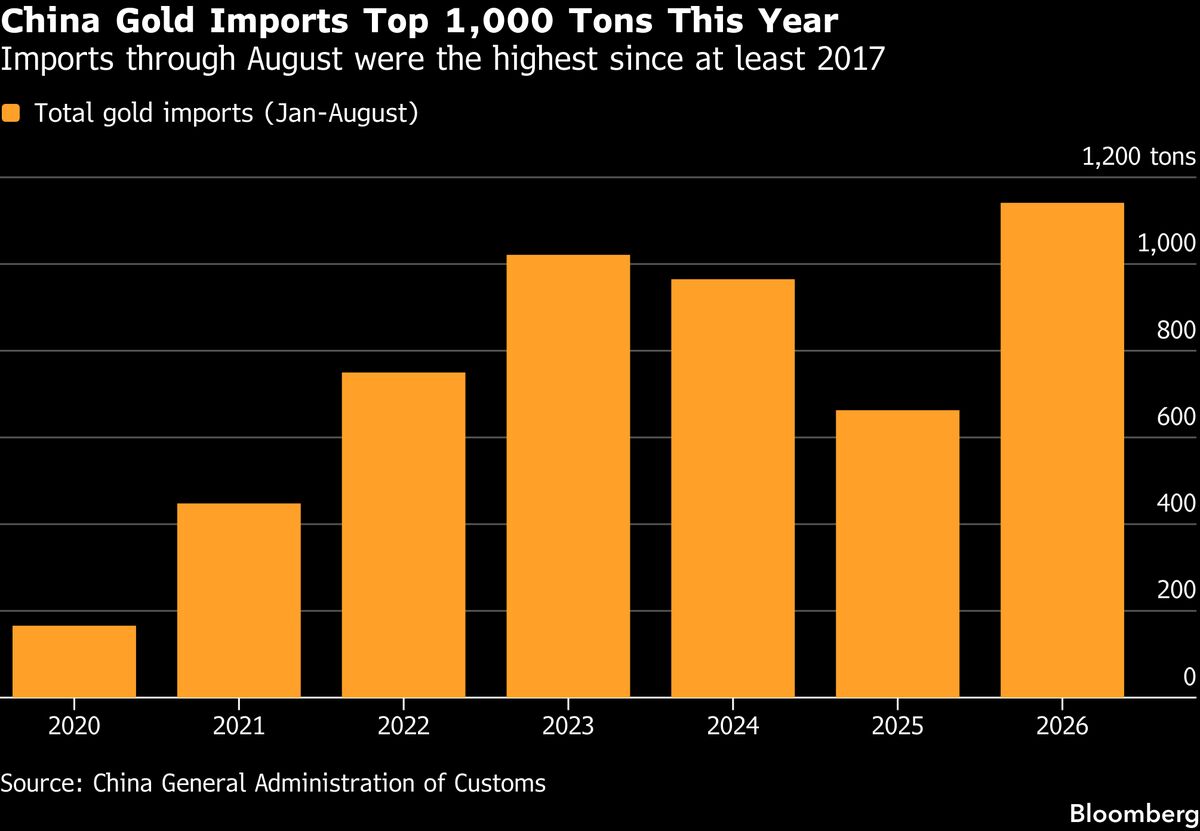
China's gold imports exceeded 1,000 tons through August, already surpassing the full-year 2025 total and reaching a record for the available customs-data period since 2017. Strong domestic investment demand has kept Chinese gold prices at a modest premium to global benchmarks, while lower international prices and a stronger yuan have made imports more attractive. The figures signal robust Chinese physical-gold demand and could support the gold market.
Analysis
The actionable signal is not headline Chinese demand but the persistence of an onshore premium: it indicates that physical buying is absorbing metal despite lower international prices, tightening the arbitrage link between Shanghai and London. This creates a near-term floor for XAU/USD and supports bullion-backed ETFs (GLD, IAU) more directly than gold miners, whose equity returns remain dominated by operating-cost inflation, reserve replacement and broader equity-beta. A sustained firm CNY would further lower local-currency acquisition costs and can reinforce demand even without a fresh geopolitical shock.
Over the next 1-3 months, the key transmission channel is refinery and vault inventory: continued Chinese import absorption can reduce readily deliverable metal availability and raise the probability that COMEX/LBMA physical tightness lifts prices disproportionately versus futures positioning. The more differentiated equity beneficiaries are lower-cost, unhedged producers with meaningful FCF torque to bullion—AEM, NEM and GOLD—though this requires confirmation that gold is rising in USD rather than merely becoming cheaper in CNY. Chinese jewelry retailers are less clean beneficiaries: investment-led bar demand can crowd out discretionary jewelry spending and compress inventory turns if the price subsequently rebounds.
Consensus may overstate the durability of the demand impulse. A domestic premium can close abruptly if the yuan weakens, authorities tighten import quotas, or retail investors rotate toward domestic equities/property alternatives; in that scenario, imports fall without requiring a collapse in global gold demand. Falsification for a constructive bullion view is a sustained Shanghai premium near zero or negative alongside a weaker CNY and rising Chinese ETF redemptions; conversely, a widening premium while real US yields decline would justify adding exposure.
For the 6-18 month horizon, recurring physical accumulation is structurally supportive of gold's marginal-buyer base, but it does not eliminate the dominant macro risk: a renewed rise in US real yields and a stronger dollar can overwhelm physical demand. Treat the signal as a floor-strengthening factor rather than a standalone breakout catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- Initiate a modest long GLD or IAU over the next 1-2 weeks only if the Shanghai-London premium remains positive and USD/CNY stays below its 50-day moving average; target a 6-10% bullion move over 3 months, with a stop/reassessment if the premium turns negative for two consecutive weeks.
- Pair long AEM versus short GDX for a 3-6 month horizon if spot gold closes above its 100-day moving average: favor AEM's lower jurisdictional and operating-risk profile over the diversified miner basket. Exit if all-in sustaining-cost guidance rises materially or gold breaks below the prior quarter's low.
- Use a long GLD / short UUP tactical pair rather than unhedged gold exposure if the yuan remains firm; this isolates the physical-demand and dollar-softness channels. Avoid sizing this as a pure China-demand trade if US 10-year real yields are rising above recent three-month highs.
- Set an alert—not a position—for a widening Shanghai premium combined with declining COMEX registered inventory. If both persist for 4-6 weeks, add upside through 3-6 month GLD call spreads; the missing confirmation is inventory data showing physical tightness rather than import rerouting.
More News
- U.S. strikes Greenland deal for 'permanent control over security,' will send forces to Danish dog-sled outpost and reopen Cold War base: report
- Latest Oil Market News and Analysis for Sept. 22
- Paramount agrees invest $1.5 billion in domestic movies and create a board for editorial independence at CNN, CBS as part of deal for Warner Bros.
- Factbox-Key issues for this week’s Trump-Xi summit in Washington
- World Leaders Converge on United Nations General Assembly
- Here's where UBS says to invest with global yields elevated
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Track Guidance Changes Across a Coverage List With AI
- Stop Treating AI Like a Chatbot: What Are Agents, SubAgents, MCP, and Skills, and How Do They Actually Work?