
Let America Build™ Campaign Comes to Boston to Spotlight America's Growing Housing Supply Gap
Source: PR Newswire
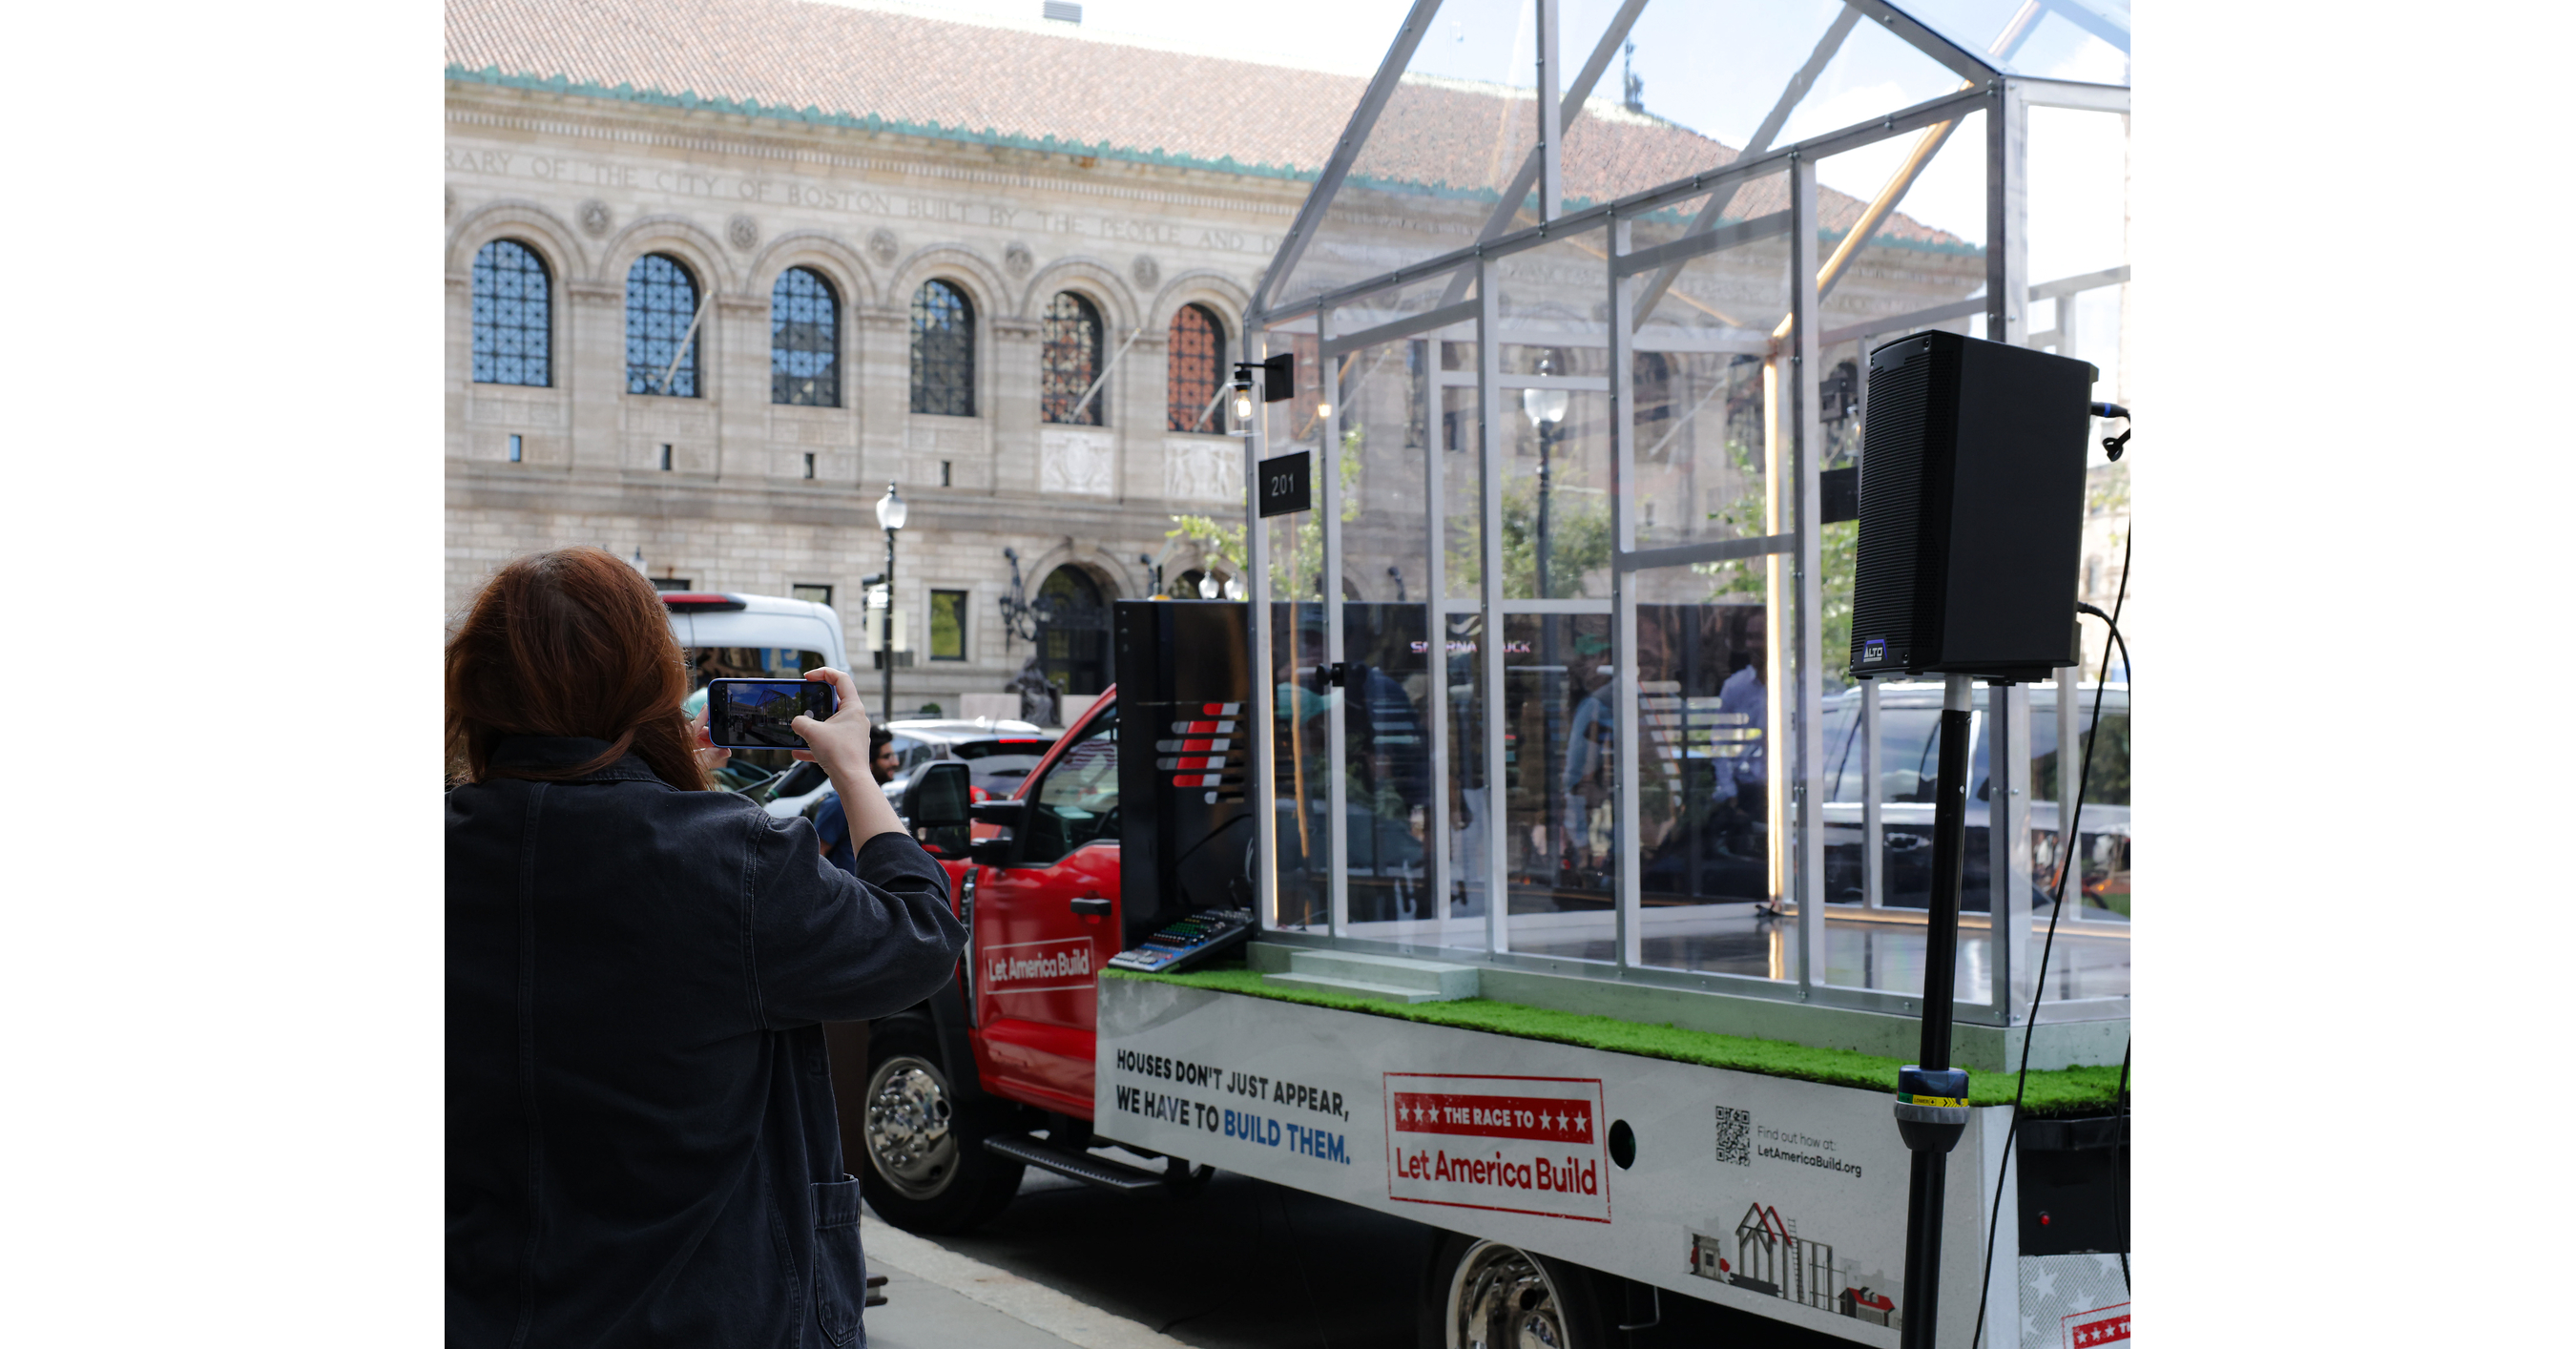
Boston active housing listings rose 15.0% year over year in August, but remained below pre-pandemic levels, underscoring the region's persistent supply shortage. The median list price was $795,000, down 0.6%, while price per square foot fell 1.5% and median time on market increased by six days, indicating modestly improved buyer leverage without a broad repricing. The Let America Build campaign highlights zoning constraints, including only 4% of land permitting multifamily housing by right versus a 12% national average.
Analysis
The direct earnings read-through for Zillow (Z) is limited: local zoning advocacy does not change near-term transaction volumes, and a broader inventory base only monetizes meaningfully once it converts into higher Premier Agent, rental, mortgage and advertising activity. The more relevant near-term signal is that buyer selectivity is rising without broad seller capitulation; this can prolong muted resale turnover and keep high-margin agent lead revenue below a normalized housing-cycle recovery despite stable home values.
Over 1-3 months, Z remains more sensitive to mortgage-rate expectations and existing-home turnover than to supply-policy rhetoric. A sustained move lower in mortgage rates would improve affordability and unlock listings, creating operating leverage in Z's residential segment; conversely, further duration pressure or weakening labor data that translates into reduced household formation would challenge consensus revenue recovery assumptions. Track weekly purchase applications, new listings and Zillow's monthly traffic/share metrics rather than campaign visibility.
The 6-18 month structural implication is more nuanced. Effective multifamily zoning reform would expand rental supply before it materially expands owner-occupied resale inventory, likely benefiting Z's rentals marketplace and property-management software ecosystem more than its core agent marketplace initially. It could also dilute incumbent-homeowner scarcity premiums in supply-constrained metros, reducing the urgency premium embedded in lead conversion, while creating a larger addressable base of landlords, developers and renters. Local implementation—not public support—is the gating variable; permitting reform, utility capacity and construction labor availability determine whether any policy change reaches housing completions.
Contrarian view: investors may over-credit incremental listings as a pure positive for portals. More supply improves consumer engagement, but portal revenue requires transactions or paid marketing budgets; in a slower-moving market, agents can reduce lead spend and developers can concentrate advertising with dominant local brokers. Z's share gains and monetization per transaction must therefore outpace any cyclical pressure on agent marketing budgets for the equity to rerate.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
-0.12
Ticker Sentiment
Key Decisions for Investors
- No event-driven trade on the campaign itself; maintain Z as a housing-rate beta watch rather than adding exposure on this news. Reassess after the next monthly existing-home-sales, purchase-application and new-listings data, with a 1-3 month horizon.
- Conditional long Z: initiate only if 30-year mortgage rates decline by at least 50bp from current levels and purchase applications/new listings inflect positively for 4-6 consecutive weeks. Upside comes from transaction-led revenue recovery and operating leverage; invalidate if agent/IMT revenue guidance or paid-agent metrics weaken at the next earnings update.
- For structural supply-reform exposure, prefer a watchlist of multifamily-linked beneficiaries—AMH, INVH and construction proxies such as LEN or TOL—rather than treating Z as the primary policy beneficiary. Do not deploy until there is city/state-level zoning enactment plus permit-volume confirmation; policy announcements without permits are not investable evidence.
- Monitor Z versus Compass (COMP) and Redfin (RDFN) as a competitive spread: if inventory rises but transaction velocity remains weak, favor Z's traffic/platform model over brokerages with greater transaction and agent-cost exposure. Reverse the relative view if Z's monetization per transaction deteriorates while brokerage commission volumes recover.
More News
- History shows financial calamities occur when rates rise rapidly like this: 'Something always breaks'
- Trump, Xi Address AI, Taiwan During State Visit
- SEBI Allows Portfolio Managers to Invest Overseas, Short Equity Options
- Exclusive-How firms linked to sanctioned Chinese cotton giant sell clothes to U.S
- U.S. government seeks to join Elon Musk in challenge against EU's fine on X
- 30-year fixed mortgage rate jumps sharply Thursday to 7.45%
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What a Concept From Nature Tells Us About How C-Suite Executives Actually Think About AI
- How to Track Earnings Call Sentiment Across Companies