
Envision Energy dévoile son éolienne marine EN-252/16.7, qui affiche des performances et une fiabilité élevées dans des environnements soumis à des vents violents
Source: PR Newswire
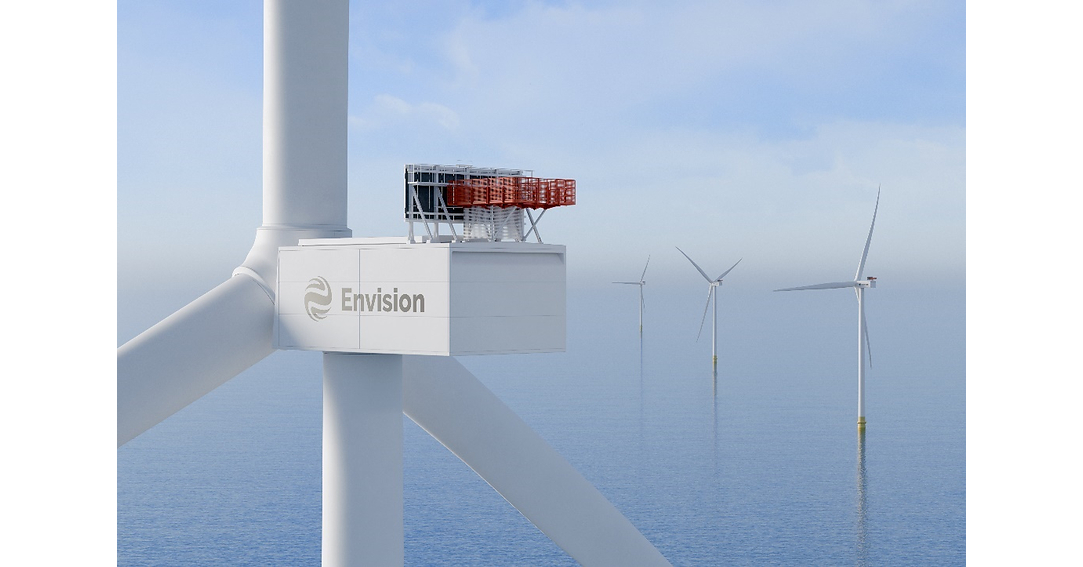
Envision Energy a lancé l'éolienne offshore EN-252/16.7, d'une puissance nominale de 16,7 MW, destinée aux marchés internationaux et aux environnements marins à vents violents. Pour un parc de 1 GW, la société estime que ce modèle peut accroître la production annuelle de 1 à 2 %, réduire le nombre d'éoliennes d'environ 10 % et abaisser le coût actualisé de l'énergie de 2 à 4 %. La turbine intègre le système Galileo basé sur l'IA, utilisé sur plus de 20 000 éoliennes, afin de détecter les défaillances potentielles un à six mois à l'avance et de réduire les coûts de maintenance imprévus.
Analysis
This is strategically more relevant to European offshore-wind procurement than to near-term public-equity earnings. A credible 16–17MW alternative expands the qualified supplier set against Vestas (VWS.CO), Siemens Energy (ENR.DE) and GE Vernova (GE), potentially reducing OEM pricing power precisely as Western manufacturers seek to restore margins through disciplined bidding. The key issue is bankability: developer acceptance, certification, warranty terms and local-service capability—not claimed turbine performance—will determine whether Envision converts an engineering launch into addressable European orders.
For VWS.CO and ENR.DE, the immediate read-through is modestly negative for terminal-value assumptions rather than 2026 estimates. Larger turbines lower balance-of-plant cost per MW, which can improve project economics for developers such as Ørsted (ORSTED.CO), RWE (RWE.DE) and EDPR (EDPR.LS), but only if reliability is proven; a single serial defect in an ultra-large platform can erase years of LCOE savings through vessel downtime and warranty provisions. Developers may gain negotiating leverage before they gain real supply optionality.
Over 6–18 months, the more consequential second-order effect is pressure on European localization policy. If Chinese OEM participation rises, EU content, cybersecurity and grid-control requirements could become binding constraints; tougher procurement rules would protect VWS.CO/ENR.DE but raise project capex and slow auction build-out. Consensus is likely to over-credit headline LCOE gains: offshore projects remain constrained by financing costs, transmission availability, installation vessels and permitting, none of which improve materially from a product announcement.
No directional trade is warranted solely from this release. Monitor named European pilot orders, DNV/IEC certification, financing by non-Chinese lenders, and disclosed warranty pricing; these are the gating events that would turn competitive rhetoric into estimate risk for incumbents.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- Maintain a 1–3 month watch rather than trade VWS.CO or ENR.DE on the announcement; escalate to a tactical underweight only if Envision secures a European commercial order with third-party certification and project finance backing. Falsifier: European policy exclusion or absence of qualified orders through the next tender cycle.
- Use any broad offshore-wind selloff to selectively accumulate RWE.DE or ORSTED.CO only after project-level capex guidance confirms lower turbine/installation cost; turbine competition helps equity value only where power-price, financing and grid assumptions remain intact.
- For a 6–18 month relative-value hedge, consider long VWS.CO / short ORSTED.CO only if EU local-content restrictions tighten: protected OEM order visibility should outperform developers facing higher equipment costs and delayed build schedules. Exit if auction terms compensate developers for localization costs.
- Track GE and ENR.DE quarterly warranty provisions, offshore order margins and backlog pricing. A widening warranty reserve or weaker-than-expected offshore margin—not a competitor launch—is the actionable confirmation for an incumbent short.
More News
- Trump Versus Xi: How Their High-Stakes Summits Compare
- SEBI Allows Portfolio Managers to Invest Overseas, Short Equity Options
- Trump, Xi Address AI, Taiwan During State Visit
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- China's Xi urges U.S. to cooperate on AI
- Akamai secures $11.6B cloud deal with Anthropic for AI workloads