
Lilly breaks ground in Houston, one of ten U.S. manufacturing sites announced since 2020
Source: PR Newswire
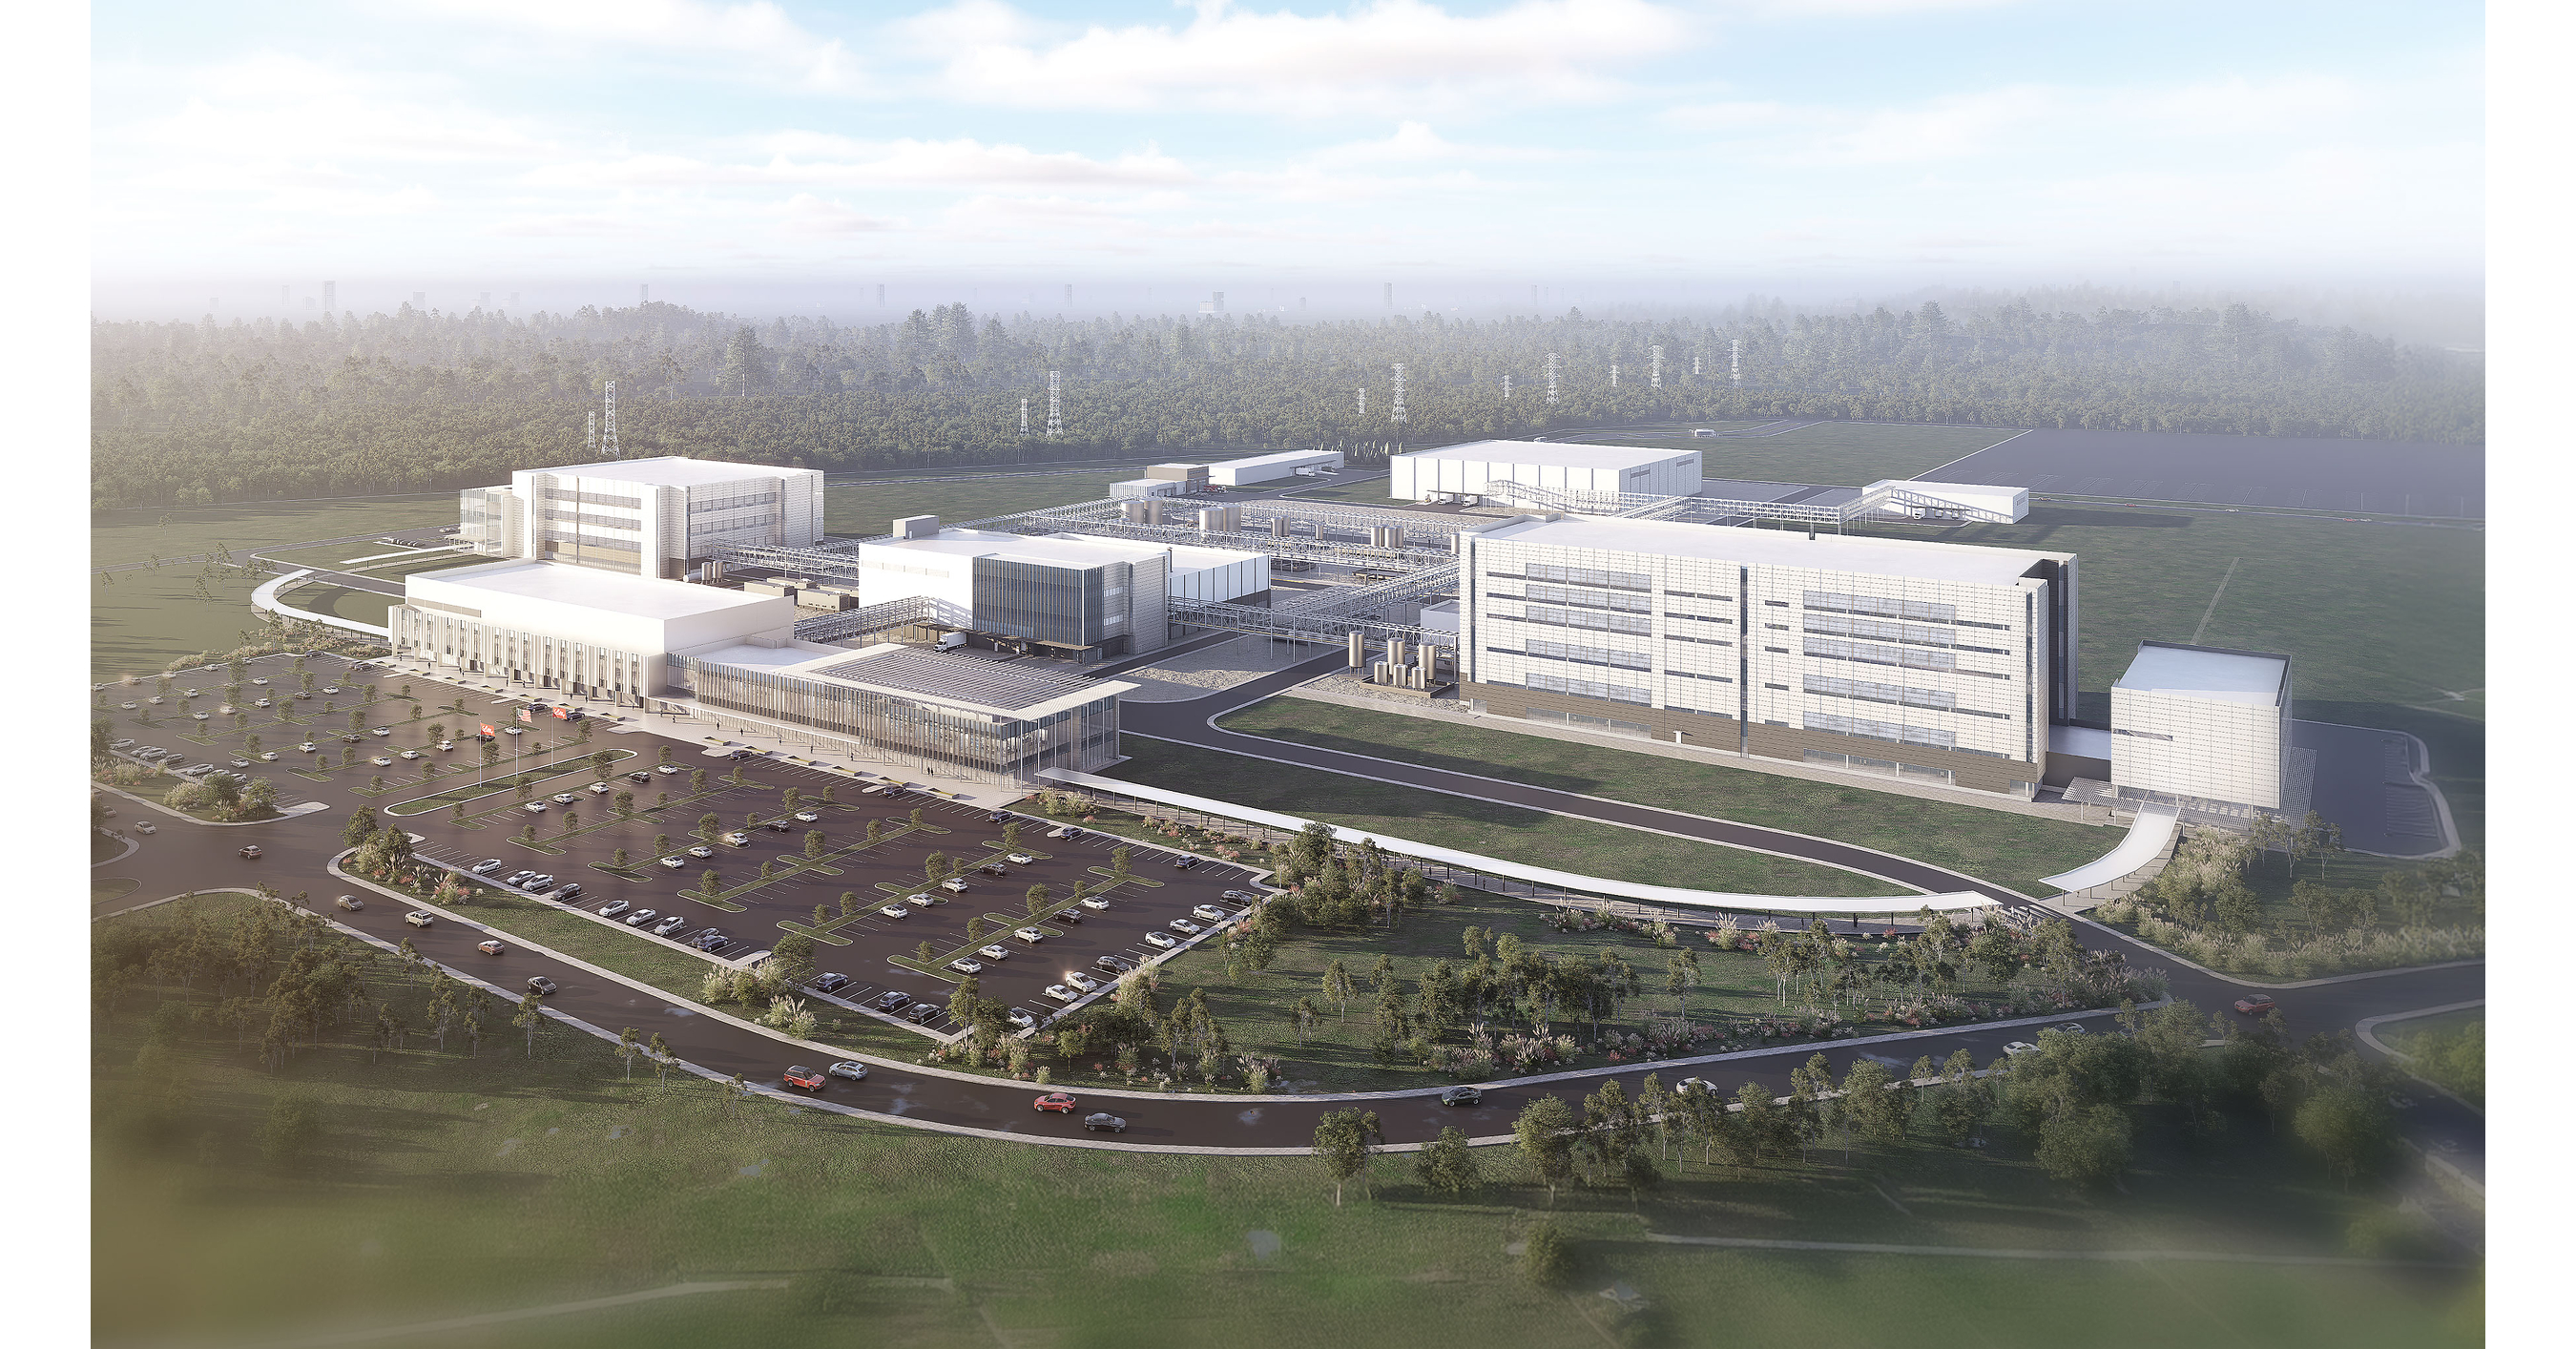
Eli Lilly broke ground on a $6.5 billion Houston active-pharmaceutical-ingredient facility, part of its $50 billion U.S. medicine-production reshoring program. The site will manufacture oral GLP-1 obesity drug Foundayo (orforglipron), other small-molecule medicines and advanced therapeutics, supporting a targeted global Foundayo rollout in 2027. Lilly expects the facility to create more than 600 high-wage permanent jobs and 4,000 construction jobs, while committing $15 million to workforce training and scholarships with San Jacinto College.
Analysis
This is strategically more important as a gross-margin and availability hedge than as a near-term revenue catalyst. Oral small-molecule GLP-1 capacity reduces dependence on constrained peptide fill-finish ecosystems and should lower the marginal cost of serving international obesity demand once the site is qualified; however, a greenfield API asset is unlikely to affect supply materially for several years. The nearer financial implication is elevated capex and start-up expense, leaving LLY’s valuation increasingly dependent on oral-GLP-1 adoption, pricing durability, and execution rather than another capacity announcement.
The competitive consequence is potentially sharper for Novo Nordisk (NVO): a scalable oral product could broaden access through lower manufacturing complexity, easier distribution, and less cold-chain intensity, shifting competition from supply allocation toward formulary price and persistence. CDMOs with meaningful peptide/API scarcity rents—particularly Lonza (LONN.SW) and Samsung Biologics (207940.KS)—face a long-dated risk of customers internalizing more high-value production, though Lilly’s expansion alone is not sufficient to impair earnings. Chugai (4519.T), as the originator/licensor, is a indirect beneficiary if global volume ramps, but royalty economics should be confirmed before assigning material upside.
Consensus may overread the headline as immediate confirmation of blockbuster economics. The key 1-3 month catalyst is clinical data in diabetes and sleep apnea plus evidence of payer coverage and discontinuation rates; those variables determine demand elasticity far more than announced capacity. Falsify the constructive LLY view if oral-GLP-1 guidance fails to rise after data, net pricing weakens materially versus injectable GLP-1s, or construction/qualification timing extends enough to raise aggregate capex without matching volume commitments.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- Maintain, do not add aggressively, to LLY on this release alone; use any 5-8% pullback around clinical-data or earnings volatility to build a 6-18 month position only if management quantifies commissioning timing, capacity, and incremental capex. Upside is oral-GLP-1 volume/margin expansion; risk is multiple compression if investment outpaces revenue conversion.
- Establish a 6-12 month relative-value watch: long LLY / short NVO only after confirming comparable oral-product efficacy, tolerability, and U.S. net-price positioning. Use a 10-12% adverse relative-performance stop; the thesis fails if NVO preserves formulary exclusivity or Lilly’s persistence profile is inferior.
- Monitor LONN.SW and 207940.KS for a 6-18 month de-rating opportunity, not an immediate short. Act only if disclosed GLP-1-related utilization, backlog, or pricing weakens while pharma customers accelerate captive small-molecule/API investments; absent such evidence, their diversified biologics exposure makes the signal too weak.
- Set an event alert for the upcoming diabetes and obstructive-sleep-apnea readouts: positive data without a corresponding increase in LLY demand/capacity guidance would indicate that payer access, rather than clinical breadth, is the binding constraint and argues against chasing LLY.
More News
- Eli Lilly CEO tells CNBC one-third of new GLP-1 pill patients are taking Foundayo, as drugmaker ramps up production
- CNBC Daily Open: All that glitters is another U.S.-China détente
- Why Novo Nordisk Stock Just Crashed
- Morgan Stanley's top picks list trounced the S&P 500 the last 12 months. Here are the new members
- Smart ring maker Oura, shareholders look to raise up to $2.2 billion in US IPO
- Oppenheimer reiterates Viking Therapeutic stock rating on maintenance data potential