
Společnost Envision Energy představuje mořskou větrnou turbínu EN-252/16.7, která nabízí vysoký výkon a spolehlivost v podmínkách silného větru
Source: PR Newswire
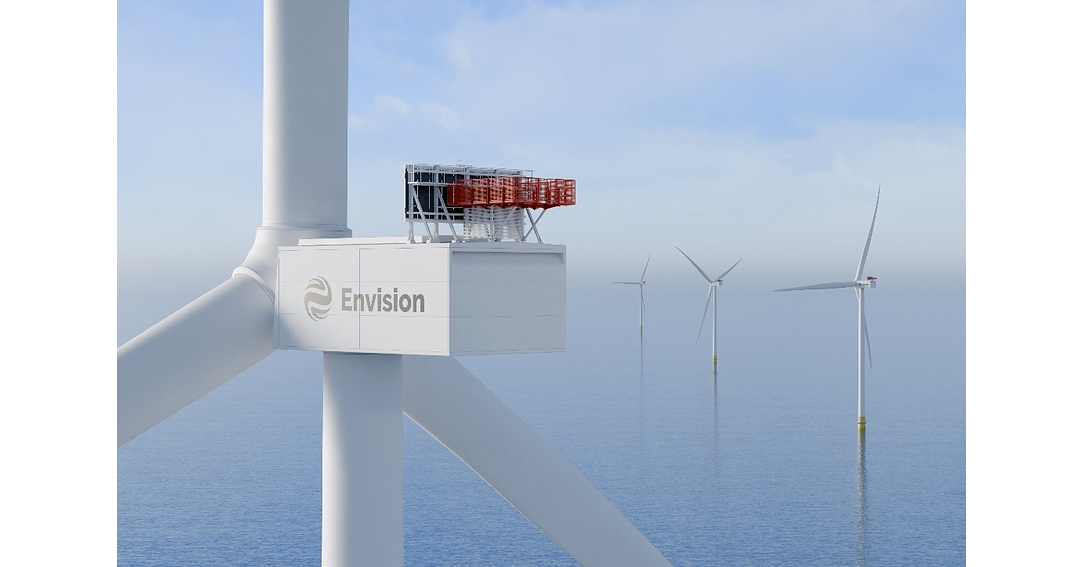
Envision Energy launched its EN-252/16.7 offshore wind turbine, rated at 16.7MW and designed for high-wind European offshore markets. The company says a gigawatt-scale wind farm using the model could generate 1-2% more annual energy, require about 10% fewer turbines and reduce levelized energy costs by 2-4% versus currently available models. AI-based Galileo monitoring, already deployed across more than 20,000 turbines, is intended to identify failures roughly one to six months in advance and lower lifecycle maintenance costs.
Analysis
The relevant market signal is not a near-term revenue event but another data point in offshore-wind turbine commoditization. A credible Chinese 15MW+ platform raises the probability that European project sponsors regain a third procurement option as Vestas (VWS.CO), Siemens Energy’s Siemens Gamesa (ENR.DE), and GE Vernova (GE) attempt to restore offshore margins after years of warranty and execution losses. The primary pressure point is future bid pricing rather than installed-base service revenue: a lower-cost entrant can force OEMs to accept thinner equipment margins to preserve pipeline, while developers such as Ørsted (ORSTED.CO), RWE (RWE.DE), and EDP Renováveis (EDPR.LS) gain negotiating leverage.
The claimed project-economics improvement should be treated as unverified until independent certification, European type approval, financing-bank acceptance, and a firm order are disclosed. Larger rotors reduce balance-of-plant costs only if vessel availability, port constraints, blade transport, and installation reliability scale with them; a single serial defect can erase multiple years of nominal LCOE savings. Over 6-18 months, the more important question is whether EU local-content, cybersecurity, and supply-chain-security rules prevent Envision from converting technical capability into European market share—an outcome that would protect incumbent OEM pricing despite the technology gap.
Consensus may overread this as immediately negative for European OEMs. Incumbents retain grid-code relationships, local service networks, project-finance credibility, and installed-base economics, while Chinese offshore platforms have limited demonstrated operating history in North Sea conditions. Conversely, the development is incrementally positive for offshore developers if it broadens the qualified supplier pool, potentially lowering rebid costs and reducing the risk that turbine OEM capacity—not power-price assumptions—determines project returns.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No directional trade on the launch alone; set an alert for an independently certified European order or named project award. A firm EU order would be a 1-3 month negative catalyst for VWS.CO and ENR.DE offshore pricing expectations and a positive read-through for ORSTED.CO/RWE.DE development returns.
- Maintain a watchlist pair: long ORSTED.CO or RWE.DE / short VWS.CO, sized only after evidence of Chinese OEM qualification in a European tender. The thesis is developer CAPEX relief versus turbine-price competition; invalidate if EU procurement restrictions explicitly exclude the supplier or Vestas demonstrates stable offshore order margins.
- For GE, avoid extrapolating a direct impact until its offshore order-book and warranty provisions show competitive pressure. GE’s valuation is more exposed to U.S. onshore wind, power equipment, and electrification; an offshore-specific short is cleaner through VWS.CO or ENR.DE if pricing deterioration becomes visible.
- Monitor European Commission trade-security actions, bankability decisions by major lenders, and offshore tender bid spreads over the next 6-12 months. These are the gating variables; technical claims without certification, project financing, and service commitments should not change earnings estimates.
More News
- Saudi, Turkish, Pakistani chiefs plan urgent talks amid Yemen fighting
- Trump Versus Xi: How Their High-Stakes Summits Compare
- Trump, Xi Address AI, Taiwan During State Visit
- SEBI Allows Portfolio Managers to Invest Overseas, Short Equity Options
- China's Xi urges U.S. to cooperate on AI
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent