
BYD Eyes Idled Stellantis Plant in Brampton as Trump Tariffs Bite Canada
Source: Bloomberg
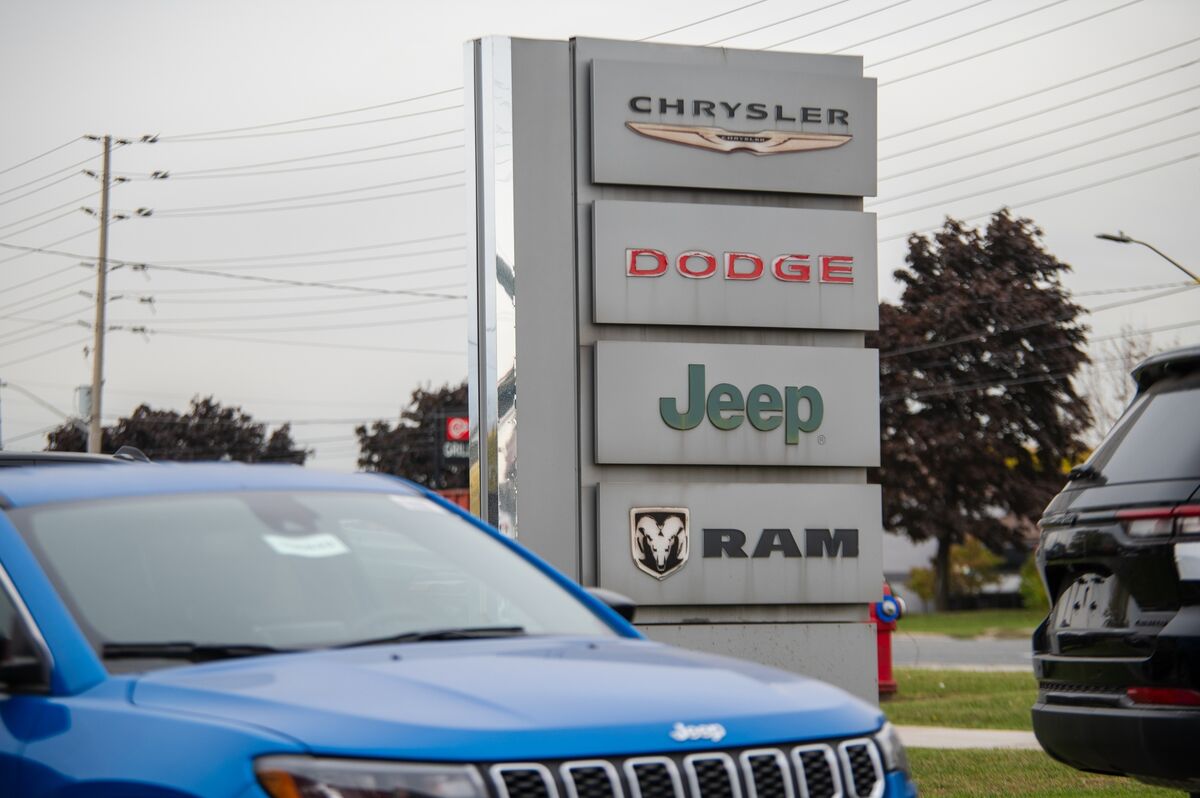
The article frames Canada–North American auto supply-chain resilience as a difficult “rescue” problem, citing decades of tightly linked production networks. It also notes that metals tariffs may be more “symbolic” than materially trade-relevant, suggesting limited near-term economic impact despite ongoing debate around trade diversification.
Analysis
The market is likely overpricing the tariff angle and underpricing plant economics. For autos, metal inputs are a low-single-digit share of vehicle value, so “symbolic” tariffs tend to create headline volatility for steel names without materially improving OEM margins or preserving high-cost capacity. The real winners are the lowest-cost, most flexible North American producers with the ability to shift content across the U.S./Mexico footprint; the losers are Canadian assembly and parts assets that depend on subsidies and high utilization to clear fixed costs.
Second-order effects matter more than the headline: if one Canadian plant is “rescued,” that often delays rationalization rather than restoring competitiveness, which keeps overcapacity and wage pressure in the system. That is negative for suppliers with concentrated Canadian exposure such as Magna and Linamar, because underabsorbed overhead and lower run-rates show up in margins before any tariff benefit does. By contrast, GM and Stellantis can re-source and rebalance production faster than local politicians can stabilize labor and energy costs.
Catalyst path: the next 1-3 months are about OEM guidance, subsidy commitments, and plant-utilization data, not the tariff announcement itself. Over 6-18 months, the structural story is supply-chain migration toward Mexico and the southern U.S., plus more aggressive automation, which reduces the political value of “saving” legacy Canadian assembly. The thesis breaks if Ottawa/provinces put enough cash behind the plant to keep utilization near full, or if trade policy expands from symbolic metals duties into broader auto-content restrictions.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
-0.05
Key Decisions for Investors
- No immediate standalone tariff trade; wait for OEM Q3 guidance and plant-funding announcements before sizing exposure.
- On any relief rally tied to government support, fade Canadian auto-exposed names: short MGA or Linamar-linked exposure versus a basket of more flexible North American OEMs over 1-3 months.
- Short US steel names on the “symbolic tariff” thesis if the group rips on headlines; use X as a liquid proxy and cover if broader auto-content restrictions are proposed.
- If you want a cleaner relative-value expression, pair long GM against Canadian auto suppliers for 2-3 quarters; the upside is from production reallocation, not tariff pass-through.
- Set a watch item on plant utilization and subsidy size: if support keeps a facility above roughly breakeven utilization for two quarters, the short thesis weakens materially.
More News
- AI Selloff Deepens in Asia as Funding Fears Mount
- Chevron CEO warns oil buffers that cushioned the Iran war shock have been ‘drained’—and diesel relief may not come until 2027
- TSMC chip capacity is ‘fierce’ battleground for AI customers, amid record quarter
- Smartphone shipments plummet as memory crisis pumps up prices
- Memory stocks are getting hammered. China and a 2029 oversupply are the big worries
- Global EV sales fall 2% in September, ending six-month growth streak
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Analyze SEC Filings With AI: A Verification-First Guide
- AI for IR Street Intelligence: Notes, Estimates, and Peers