
Shanghai Electric представляет три решения для энергетического перехода на Enlit Asia 2026
Source: PR Newswire
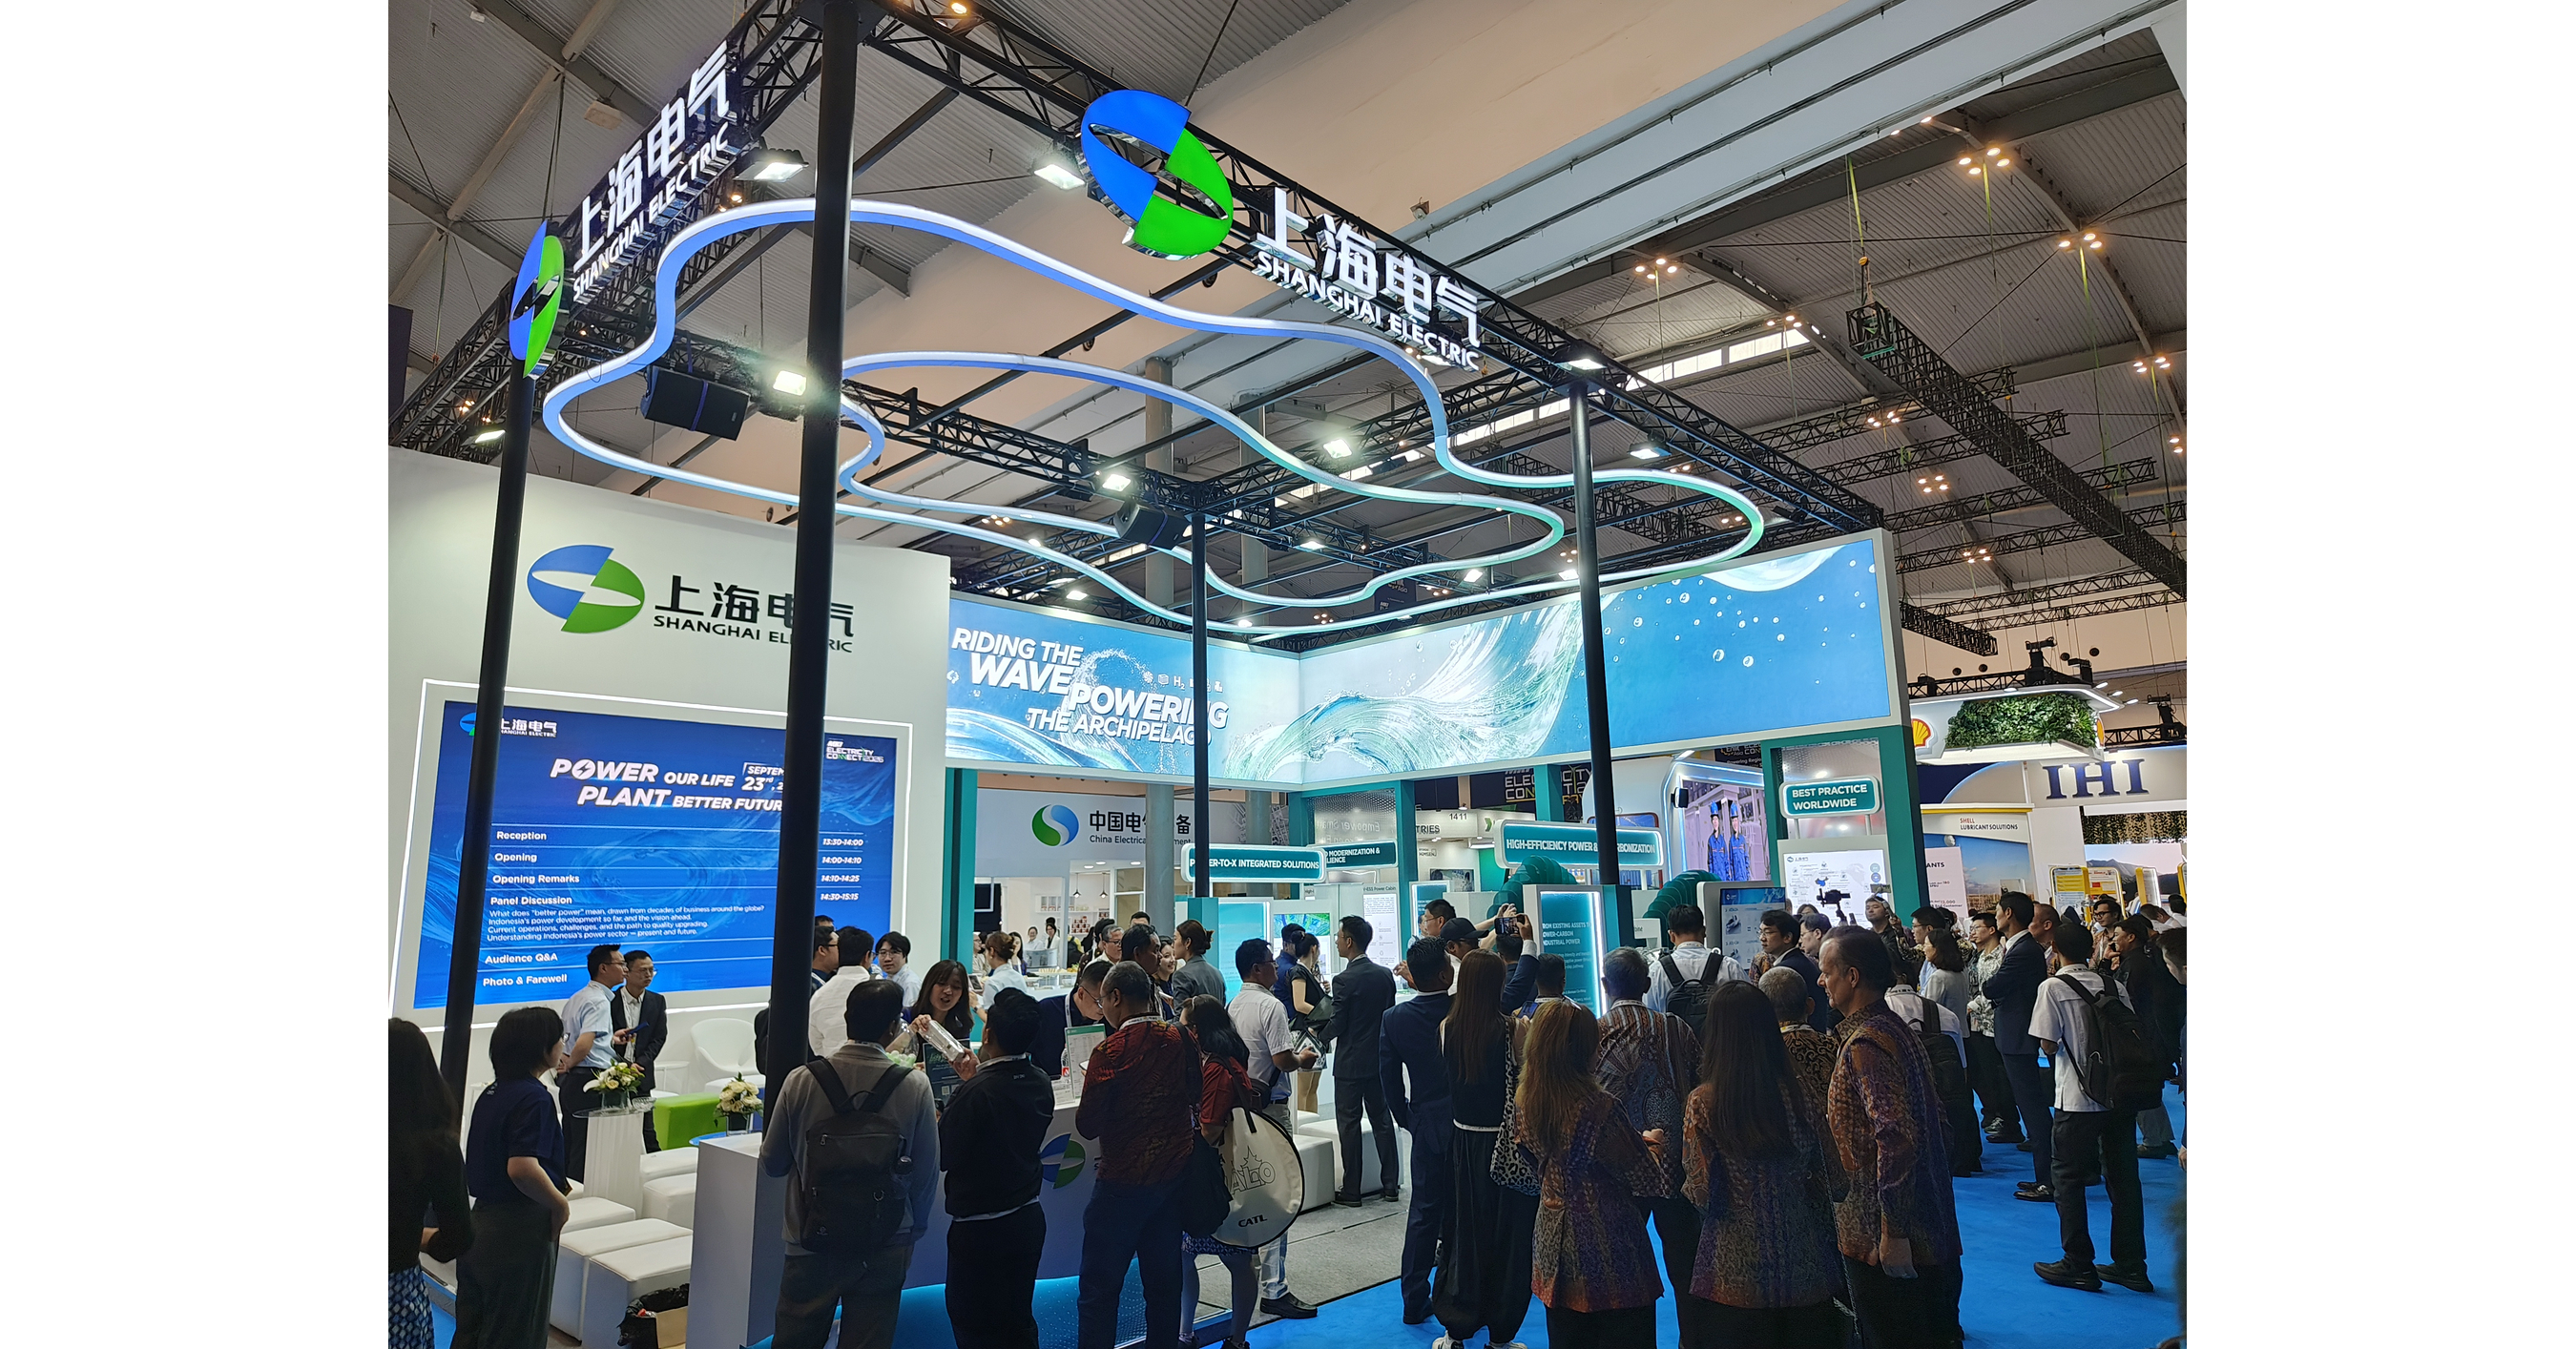
Shanghai Electric unveiled three ASEAN-focused energy-transition solutions at Enlit Asia 2026, covering thermal-power decarbonization, island-grid resilience and Power-to-X low-carbon fuels. Its gas turbines can use hydrogen blends of up to 30%, while the Jilin Taonan project has completed an 8,000-tonne green-methanol bunker delivery; Phase II targets annual output of 200,000 tonnes of green methanol and 10,000 tonnes of sustainable aviation fuel. The announcement reinforces Shanghai Electric's regional positioning in gas, renewables, storage and low-carbon fuel infrastructure, but provides no new contract awards or financial guidance.
Analysis
This is commercially non-binding marketing activity rather than an order announcement, so there is no immediate earnings read-through for Shanghai Electric (601727.SS/2727.HK). The investable signal is narrower: ASEAN grid constraints are shifting procurement from standalone renewable generation toward grid-forming equipment, synchronous condensers, storage controls and flexible gas capacity. That favors established regional power-equipment vendors only where projects convert into PLN, Sarawak Energy, or Vietnamese utility tenders with funded EPC scope.
The likely competitive pressure falls on European and Japanese suppliers whose premium grid and turbine offerings face Chinese-system pricing, notably Siemens Energy (ENR.GR), GE Vernova (GEV) and Mitsubishi Heavy (7011.JP). However, local-content rules, sovereign-financing preferences, bankability requirements and service-network depth can preserve incumbent share; Chinese equipment wins may be most likely in bundled EPC contracts financed alongside generation assets, not isolated high-specification grid equipment.
Over 6-18 months, the more material ASEAN implication is that efficient gas conversion and grid stabilization can extend the operating life of regional gas infrastructure rather than create an immediate pure-renewables capex boom. Green methanol and SAF proposals remain strategically useful but economically immaterial until long-term offtake, renewable-power access and subsidy/mandate support are disclosed. The claimed project operating metrics should not be extrapolated to ASEAN profitability without contract value, payment terms, local manufacturing content and project-finance details.
Contrarian view: market enthusiasm for China’s clean-tech export push may understate execution risk in fragmented island grids and overstate near-term hydrogen-fuel demand. A sustained decline in LNG prices improves the economics of flexible CCGT, while a rise in rates or weaker Indonesian utility finances would defer both storage and grid-modernization awards; those variables matter more than conference visibility over the next quarter.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.34
Key Decisions for Investors
- No directional position in 601727.SS/2727.HK on this release. Add an alert for disclosed ASEAN contract awards above RMB1bn, backlog conversion, and receivable/payment terms; absent these, treat the news as narrative rather than a catalyst.
- Monitor a 1-3 month relative-value setup: short ENR.GR versus long GEV only if Chinese-funded ASEAN EPC awards demonstrate share loss for Siemens Energy while GE Vernova maintains service/order momentum. Falsify if ENR reports resilient gas-services orders or wins Indonesian grid contracts; avoid initiating solely on stated product capability.
- For a liquid regional proxy, prefer selective exposure to flexible-power beneficiaries over pure hydrogen narratives: monitor GEV and 7011.JP for ASEAN gas-turbine/order announcements. Enter only after funded awards, with a 6-12 month horizon; downside is LNG-price weakness, project delays, or Chinese price competition compressing turbine margins.
- Watch Indonesian PLN capex plans, local-content procurement rules and ASEAN sustainable-fuel mandates over the next 6-18 months. Binding methanol/SAF offtake agreements—not pilot production volumes—would be the trigger to reassess shipping-fuel beneficiaries such as Maersk (MAERSK-B.CO) and renewable-fuel suppliers.
More News
- Oil prices jump after Yemen’s Houthis claim attacks on Saudi facilities
- Saudi, Turkish, Pakistani chiefs plan urgent talks amid Yemen fighting
- US 30-Year Yield Hits Highest Since 2004
- Oil falls amid optimism over potential diplomatic solution to the Iran conflict
- Trump Versus Xi: How Their High-Stakes Summits Compare
- Trump, Xi Address AI, Taiwan During State Visit