
UN Week, Trump-Xi Summit and the Weakening of Global Consensus: Big Take Podcast
Source: Bloomberg
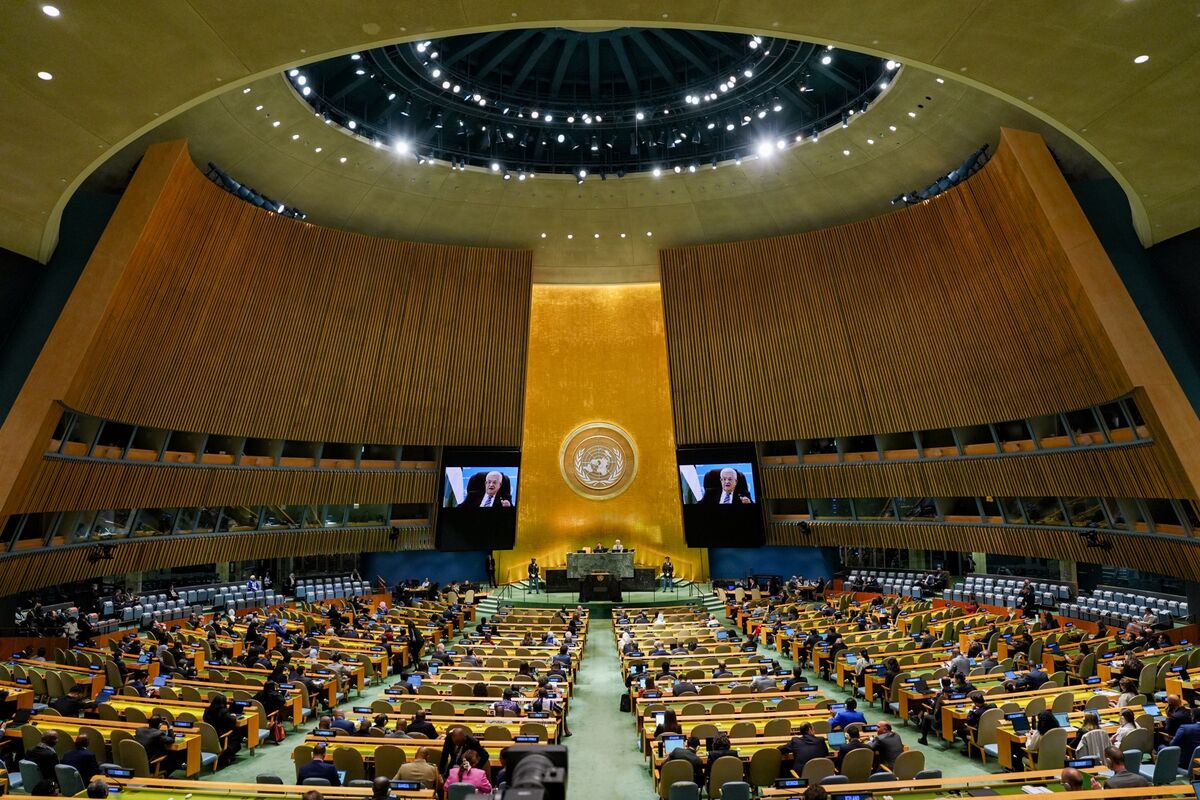
The article highlights a turbulent UN General Assembly week marked by an AI executive's dire warning, President Trump's threat to annihilate Iran, and Chinese President Xi Jinping's absence. It frames these developments, alongside a prospective Trump-Xi summit in Washington, as evidence of strain on the postwar global order and renewed uncertainty over the UN's relevance.
Analysis
There is no directly investable, new fundamental datapoint here; the near-term market implication is a modest rise in geopolitical risk premia rather than a durable directional signal. The actionable transmission channels are oil, shipping/war-risk insurance, defense procurement, and AI-policy fragmentation. Absent an actual escalation, broad equity index volatility typically mean-reverts faster than the underlying policy and supply-chain effects are reflected in earnings estimates.
Over the next 1-3 months, a weaker multilateral framework raises the probability that regional shocks are handled through bilateral coercion, sanctions, or military posturing. That favors defense primes with funded backlog and limited economic sensitivity—RTX, NOC, LMT, GD—and creates a modest call-option value in energy via XLE or Brent exposure. The less obvious loser is globally distributed hardware: AI infrastructure vendors and semiconductor supply chains remain exposed to a widening US-China technology bifurcation, where export-control changes can impair China revenue, inventory turns, and valuation multiples before reported revenue declines.
Contrarian view: investors may overpay for immediate defense and oil beta on rhetoric alone. Defense stocks require appropriations, contract awards, and production-rate increases to convert geopolitical anxiety into earnings; crude requires a physical disruption or credible supply restriction. The thesis is falsified if Iran-related shipping flows and Brent remain stable, defense budget negotiations stall, and no incremental export-control or sanctions action appears within the next quarter.
For the 6-18 month horizon, the structural trade is not simply long “geopolitics.” It is long resilient domestic production and secure supply chains versus cross-border, policy-sensitive revenue streams. Watch US-China AI export restrictions, Taiwan-related headlines, Red Sea transit costs, and Congressional defense appropriations as the catalysts that determine whether this remains a volatility event or becomes an earnings-revision cycle.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.35
Key Decisions for Investors
- No outright index-risk trade solely on this signal; maintain a 1-3 month watchlist for VIX spikes above 25 without confirmed energy or shipping disruption, which would favor selling expensive short-dated SPY/QQQ downside rather than chasing hedges.
- Use a measured 3-6 month long ITA or XAR position versus short XLI as a geopolitical-budget hedge; target a 5-8% relative move, with exit if US defense appropriations or supplemental funding loses momentum.
- Buy limited-risk 3-6 month XLE or USO call spreads only if Brent sustains above its pre-event range and tanker/war-risk premiums rise; avoid directional crude exposure on rhetoric alone. A failure of physical-market indicators to confirm within 2-3 weeks invalidates the trade.
- Monitor China revenue exposure in AI hardware: treat new export-control action as a negative catalyst for NVDA, AMD, and equipment names with China sensitivity, while favoring defense-electronics beneficiaries such as RTX and NOC. Do not initiate a semiconductor short absent verified rule changes or guidance risk.
More News
- Saudi, Turkish, Pakistani chiefs plan urgent talks amid Yemen fighting
- US 30-Year Yield Hits Highest Since 2004
- Oil falls amid optimism over potential diplomatic solution to the Iran conflict
- Trump Versus Xi: How Their High-Stakes Summits Compare
- SEBI Allows Portfolio Managers to Invest Overseas, Short Equity Options
- Trump, Xi Address AI, Taiwan During State Visit