
Shanghai Electric predstavuje na veľtrhu Enlit Asia 2026 tri riešenia energetickej transformácie
Source: PR Newswire
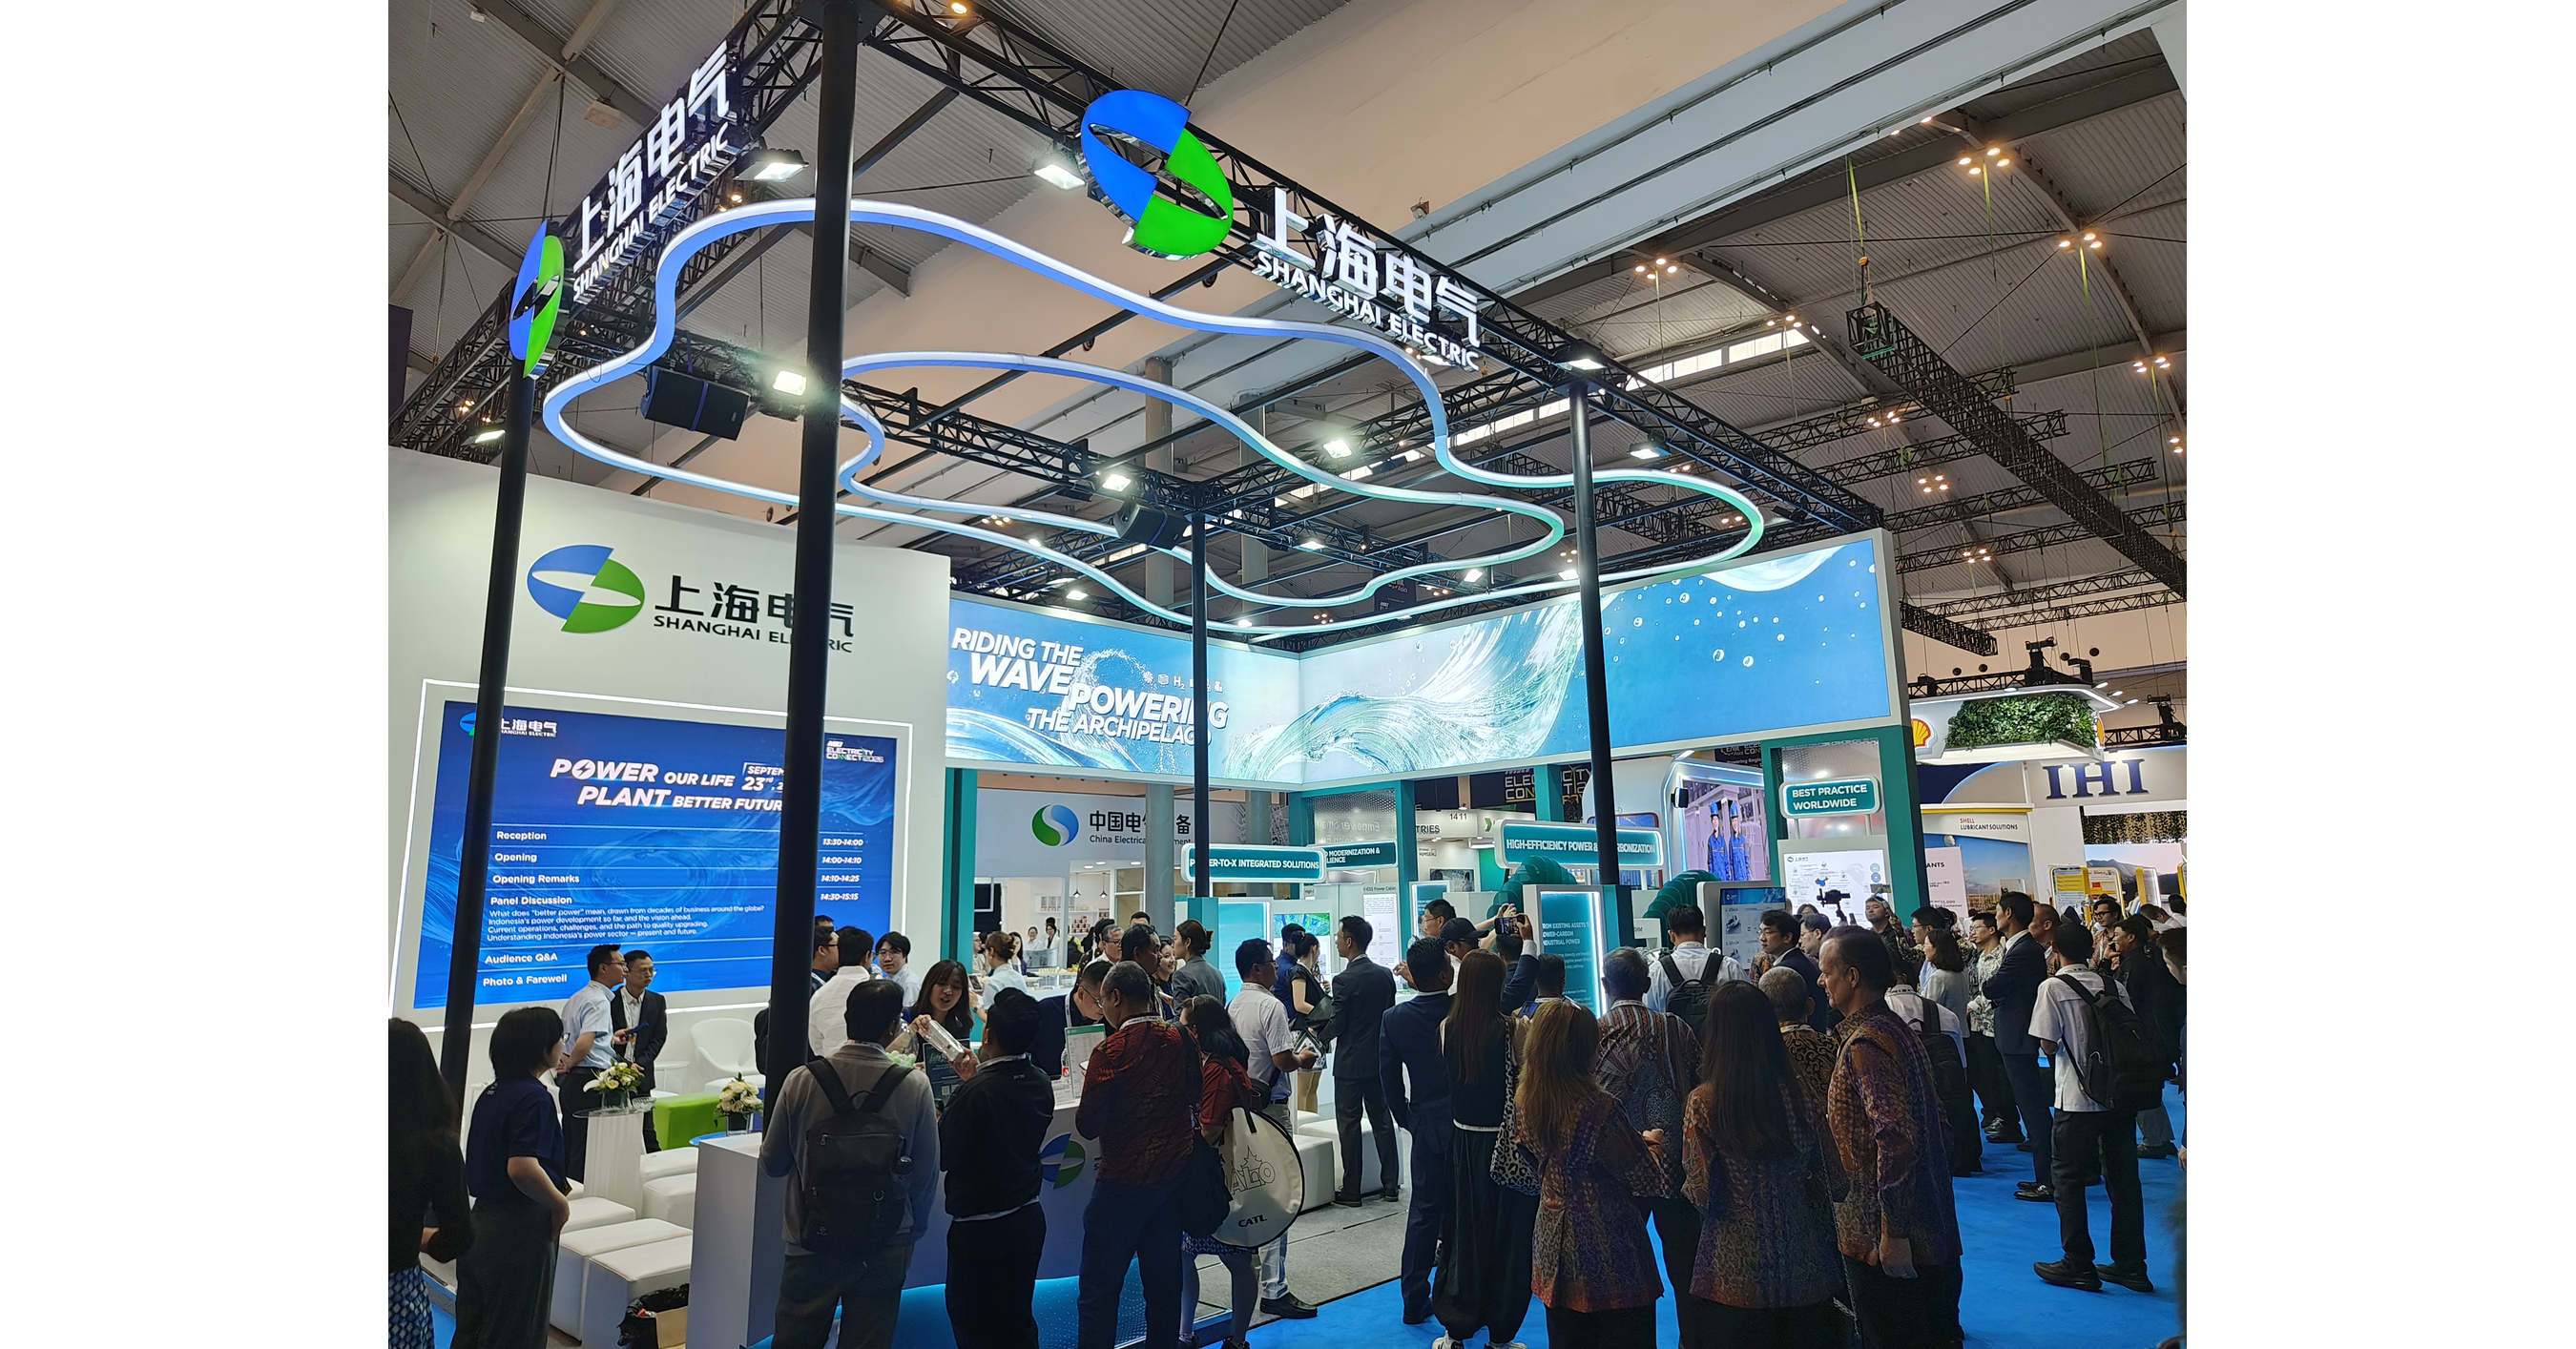
Shanghai Electric unveiled three ASEAN-focused energy-transition solutions at Enlit Asia 2026, targeting thermal-power decarbonization, island-grid resilience and low-carbon fuels. Its Power-to-X platform recorded an 8,000-ton single green-methanol bunkering milestone; Phase II aims to produce 200,000 tons of green methanol and 10,000 tons of sustainable aviation fuel annually. The company is leveraging existing regional projects, including Indonesia's 3x350MW Pelabuhan Ratu plant and Malaysia's 500MW Samalaju combined-cycle project, to expand its energy-equipment and green-fuel offerings across ASEAN.
Analysis
This is strategically constructive for Shanghai Electric but not yet an earnings catalyst: conference-led product marketing does not establish orders, financing, permitting, or customer acceptance. The relevant signal is that ASEAN’s grid bottlenecks create a larger addressable market for synchronous condensers, storage integration, and gas-to-power upgrades than for standalone renewable equipment; these are higher-value system packages but also longer-cycle, working-capital-intensive projects. For SSE, order conversion and contract-payment terms matter more than technology claims, given state-owned enterprise valuation discounts typically reflect cash conversion and receivables risk.
Near term (days to 1-3 months), the news is unlikely to rerate SSE absent disclosed PLN, Malaysian utility, or Vietnamese EPC awards. A potential second-order beneficiary is CATL (300750.SZ) and Chinese grid-equipment peers such as XJ Electric (000400.SZ), if island-grid storage procurement shifts from pilot deployments to utility tenders; conversely, incumbent turbine OEMs Siemens Energy (ENR) and GE Vernova (GEV) face incremental pricing pressure in smaller ASEAN combined-cycle tenders. The more material 6-18 month implication is that gas-fired flexibility may crowd out some coal retirements, extending demand for retrofit equipment while delaying pure-play renewable penetration.
Consensus may overvalue the green-fuels narrative relative to bankable demand. Green methanol remains constrained by renewable-power economics, offtake premia, and port-bunkering infrastructure; shipping decarbonization demand does not automatically translate into equipment orders for SSE. The better confirmation signal is a financed, contracted Power-to-X project with disclosed electrolyzer capacity, feedstock supply, offtake counterparty, and milestone payment schedule—not production targets.
Key falsifiers are a lack of ASEAN order disclosures by the next two reporting periods, rising contract assets/receivables without operating-cash-flow improvement, or a sustained decline in regional LNG prices that reduces the economic case for efficiency retrofits and hybrid grid systems. On the upside, a PLN procurement framework for grid stabilization or firm combined-cycle capacity would make the opportunity investable because it de-risks customer credit and tender timing.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade in SSE solely on this release; place a 1-3 month alert for disclosed ASEAN awards, contract value, advance-payment terms, and PLN-backed procurement. Upgrade only if orders are large enough to alter backlog visibility and cash-conversion guidance.
- For China A-share access, monitor a basket long CATL (300750.SZ) / XJ Electric (000400.SZ) following confirmed Indonesian or Philippine utility storage and grid-stability tenders; use tender award rather than exhibition activity as entry trigger. Thesis target: 6-12 months; exit if storage projects are awarded without domestic Chinese content or financing closes slip beyond two quarters.
- Maintain a tactical watch on long GEV versus ENR rather than short either name: ASEAN turbine competition is too small to drive consolidated earnings, while GEV’s service footprint and balance sheet provide better downside protection. Reassess only after identifiable H/F-class combined-cycle tender awards; no trade is warranted before then.
- Avoid pricing green-methanol equipment growth into SSE estimates until a project has contracted offtake and financing. A disclosed project with weak milestone payments should be treated as backlog-quality risk, not as a rerating catalyst.
More News
- Saudi, Turkish, Pakistani chiefs plan urgent talks amid Yemen fighting
- US 30-Year Yield Hits Highest Since 2004
- Oil falls amid optimism over potential diplomatic solution to the Iran conflict
- Trump Versus Xi: How Their High-Stakes Summits Compare
- Trump, Xi Address AI, Taiwan During State Visit
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent